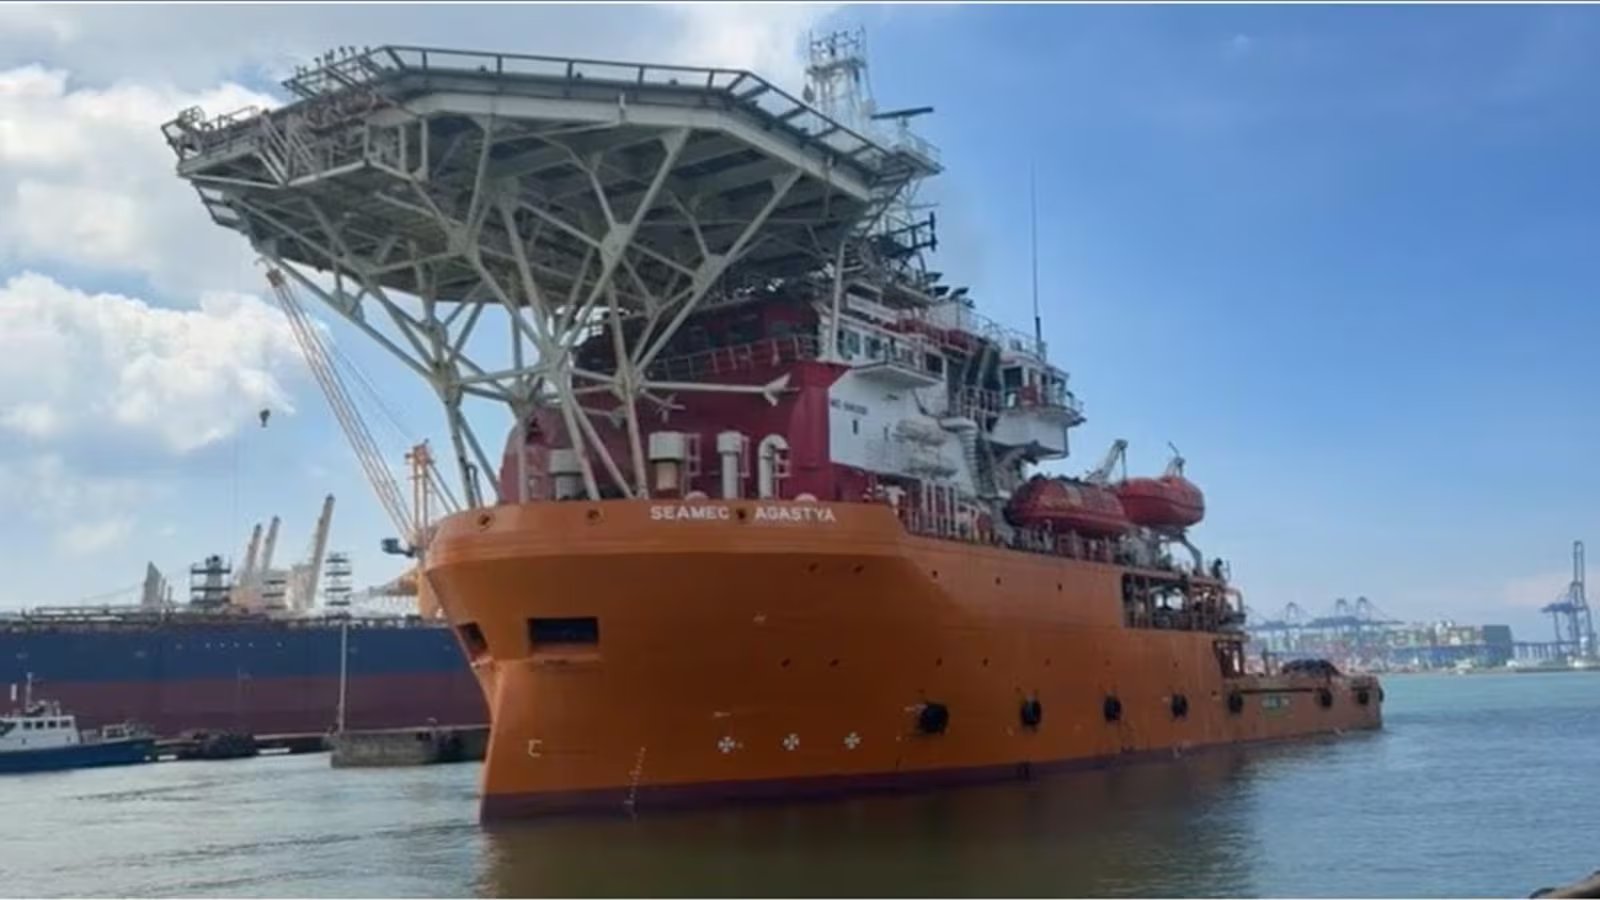
SEAMEC’s shares dipped 0.98% to ₹1,573.10 on the NSE after the filing revealed a $55 million charter contract, a sizable cash inflow that will span 1,225 days. The drop came despite the company’s clear disclosure of the deal’s terms in a Regulation‑30 filing on October 21.
The agreement, executed at 4.33 pm on October 21, involves chartering the vessel SEAMEC ANANT for ONGC‑related inspection, maintenance and repair work. HAL Offshore, the promoter holding 70.77% of SEAMEC, secured the contract under its own charter with ONGC, making it a related‑party transaction conducted at arm’s‑length terms.
Industry analysts note that offshore charter deals of this scale are uncommon in the Indian oil‑and‑gas services sector, where most firms lock vessels for 12–18 months. The 1,225‑day duration is roughly 3.4 years, providing a long‑term revenue stream that could smooth earnings volatility.
No special rights or preferential treatment were attached to the contract, and the annexure explicitly stated that there were no director appointments, share‑issuance preferences or capital‑structure restrictions. This aligns with SEAMEC’s normal‑business profile and mitigates conflict‑of‑interest concerns.
Looking ahead, SEAMEC is expected to report Q4 earnings in the first week of December. Market watchers will gauge whether the new contract boosts the company’s EBITDA margin, which has hovered around 12% in the last fiscal year. The board may also revisit dividend policy once the charter’s cash flow materializes.
The deal’s impact on revenue will unfold gradually, but the firm’s filing suggests it anticipates a substantial uptick in its offshore service ledger. Investors will likely scrutinise the next earnings release to confirm whether the contract translates into the projected revenue lift.