Tata Punch EVMahindra XEV 9SIndia EV SalesAugust 2026Electric Cars
Mahindra XEV 9S Beats Tata Punch EV By Just 78 Units In August 2026
Published: September 27, 2026
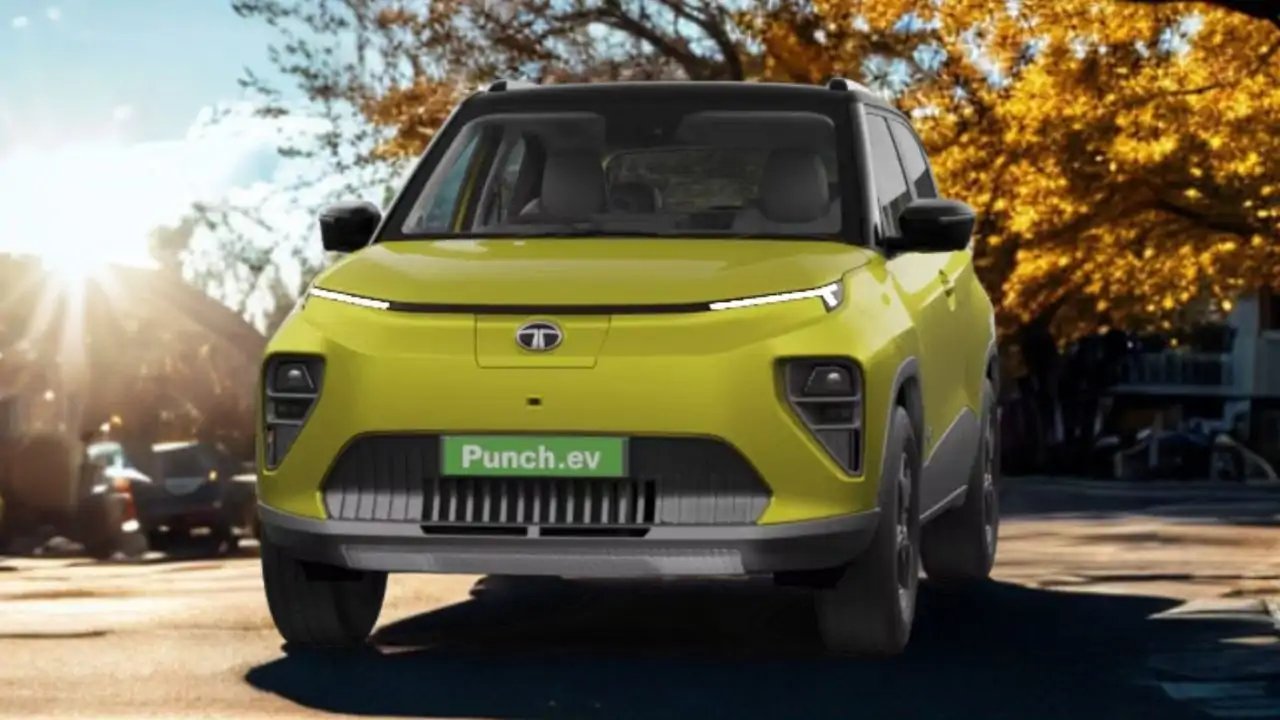
The Mahindra XEV 9S claimed the top spot in India's EV market for August 2026 with 4,508 units, edging out the Tata Punch EV by a razor-thin margin of 78 sales. The result highlights a widening gap in affordability, with the Punch EV remaining the volume king in the sub-₹10 lakh segment while the XEV 9S dominates the premium space.
It was a photo finish at the top of India’s electric vehicle sales chart for August 2026. The Mahindra XEV 9S managed 4,508 unit dispatches, while the Tata Punch EV followed closely behind with 4,430. That 78-unit difference is negligible in a market moving thousands of units a month, but it cemented the XEV 9S as the month’s best-seller. It’s a stark contrast to the price tags: the XEV 9S starts at ₹20.65 lakh (ex-showroom), whereas the Punch EV begins at just ₹9.79 lakh. Buyers are clearly willing to pay double for the three-row luxury of the Mahindra, but the volume of the Tata remains massive.
The Punch EV’s near-miss is actually a sign of strength, not failure. Dispatches for the compact SUV more than tripled year-on-year, jumping from 1,476 units in August 2025 to 4,430 this year—a 200% surge. This growth is driven by its aggressive pricing and availability in both 30kWh (Standard) and 40kWh (Long Range) battery options. Meanwhile, the XEV 9S, which launched in November last year, is holding firm in the premium segment with three battery variants (59kWh, 70kWh, 79kWh) offering ranges between 521 km and 679 km. The battle isn't really between these two; it's between the mass-market appeal of the Punch and the aspirational pull of the XEV 9S.
Behind the top two, the field thins out quickly, but the Tata Nexon EV held steady in third place with 3,975 units. That’s a 44% increase from the 2,766 units sold in August 2025, showing the Nexon EV is still a reliable workhorse for buyers seeking a mid-size crossover. It offers 30kWh and 45kWh packs starting at ₹12.49 lakh. Fourth place went to the MG Windsor EV, which saw a 18% dip to 3,705 units compared to last year’s 4,511. The Windsor, priced from ₹14.70 lakh, offers ranges of 332 km (38kWh) and 449 km (52.9kWh), but seems to be losing steam against the Tata duo.
Tata completed a hat-trick in the top five with the Harrier EV landing at number two with 2,103 units, an 18% rise from last year. Starting at ₹21.79 lakh, it competes directly with the XEV 9S but at a higher price point, suggesting buyers in the premium segment are split between Mahindra’s newer arrival and Tata’s established luxury. The August figures represent manufacturer-to-dealer dispatches, so actual retail registrations might shift the rankings slightly, but the trend is clear: the top five are dominated by SUVs, and the sub-₹15 lakh segment is where the real volume war is being fought.