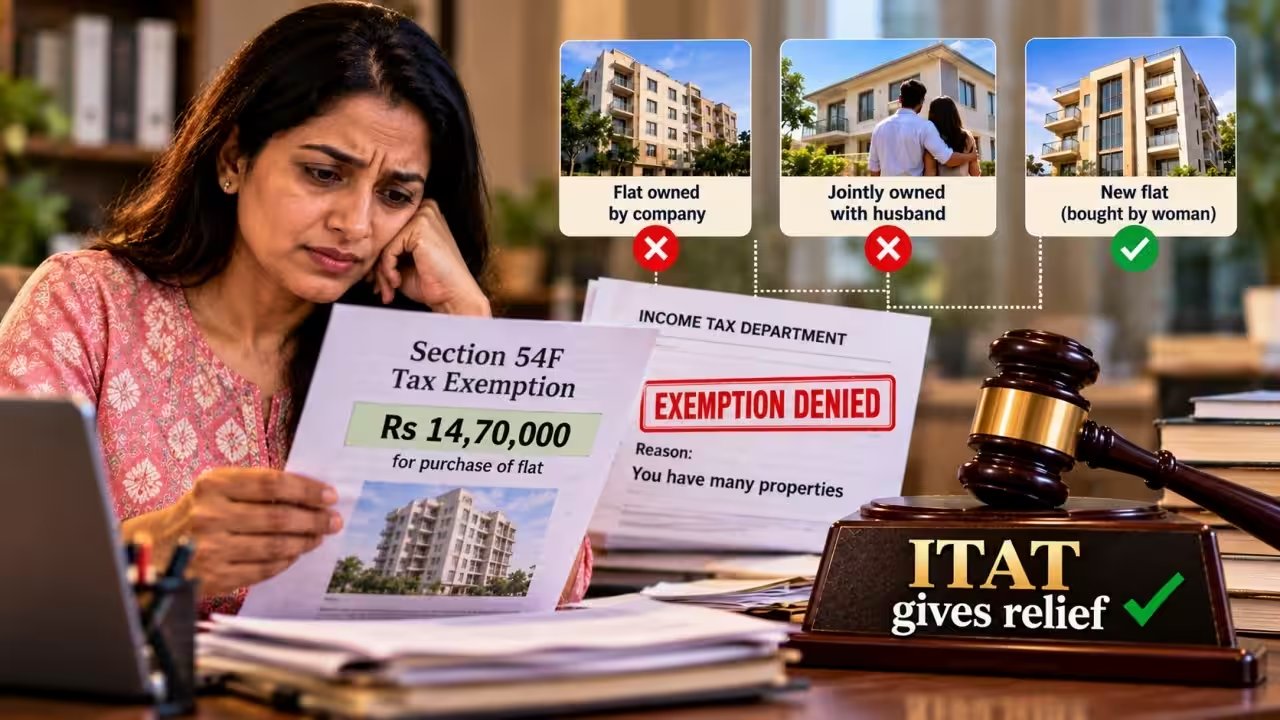
On September 10, 2026, the Income Tax Appellate Tribunal ruled that a woman from Nagpur was entitled to a Rs 14.70 lakh deduction under Section 54F, overturning the Income Tax Department’s earlier assessment that she owned multiple properties.
The Department reopened her assessment for AY 2015‑16 after she claimed the deduction, arguing she owned more than one residential house. The assessing officer denied the deduction, setting her taxable income at Rs 16.70 lakh.
The case involved three houses: a company property where she was a director, a jointly owned flat with her husband that she did not contribute to, and the new house she sold. The ITAT held that the company property could not be counted as hers and that the joint flat did not disqualify her.
The tribunal noted that fractional or joint ownership does not automatically constitute exclusive ownership for 54F eligibility, citing previous judgments. It concluded she met the conditions and granted the deduction of Rs 14.70 lakh.
The ruling clarifies that association with a company or joint ownership is not a blanket bar, easing future claims for taxpayers with similar holdings. The taxpayer can now file a revised return and claim the deduction, while the Department may have to reassess similar cases.