LouisianaInsurance LawConstruction DefectCivil LitigationReal Estate
Louisiana Court Awards $448,000 After Unlicensed Contractor’s Failed Bulkhead Shifts Home
Published: November 2, 2026
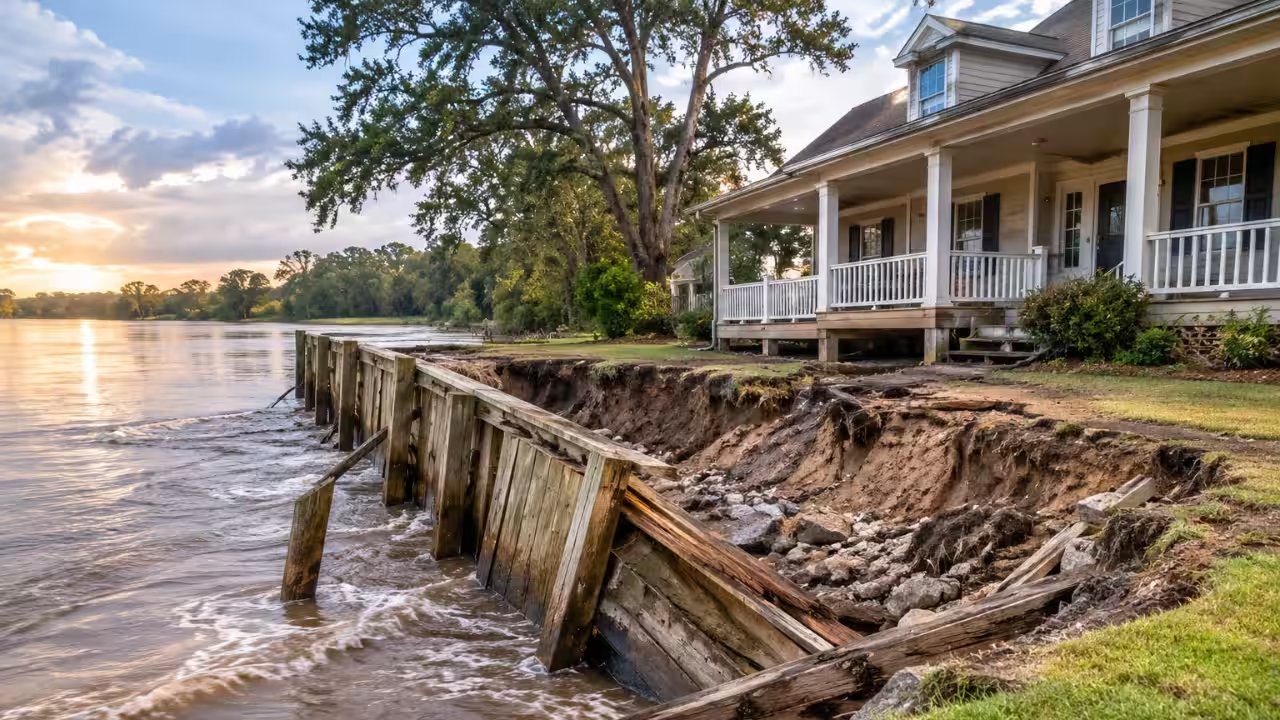
The Louisiana Court of Appeal, Third Circuit, awarded Elizabeth Molbert $448,431.34 on October 30, 2026, after a $32,500 bulkhead built by unlicensed contractors failed and structurally compromised her riverfront home. The court removed Molbert’s 25% share of fault and ordered Travelers Property Casualty to cover most damages, ruling that the contractor’s lack of license voided the insurance exclusion clauses.
Elizabeth Molbert bought her Calcasieu River home in 2009 for $109,000, hoping the water would stay put. It didn’t. In June 2016, she hired Kenko Bulkhead & Marine Services for a $32,500 job: a 130-foot wooden barrier to stop erosion. The structure was supposed to be a shield. Instead, it became the trigger for a structural disaster. When that barrier collapsed during a May 2017 flood, it didn’t just wash away. It pulled the house with it. Because Kenko had anchored the new wood to the existing house pilings, the failure caused the entire structure to shift.
Molbert’s repairs ran $266,372.75. She spent another $167,058.59 replacing the wooden fence with engineered steel. Liberty Mutual paid her $165,000 under her flood policy, but that wasn’t enough to cover the hole in her budget. In March 2018, she sued Kenko, its insurer Travelers Property Casualty, and the two men behind the company, Kenneth Cooley and Glenn Beier. The core accusation was simple: they claimed to be licensed contractors. They weren’t.
The jury, meeting in September 2024, agreed Kenko was mostly at fault. They assigned 75% of the blame to the defendants and 25% to Molbert. That split cut her original award down to $332,573.50. But the appeals court looked closer at the licensing issue. Under Louisiana law, a construction contract signed by unlicensed workers is an absolute nullity. This technicality killed Travelers’ argument that their policy’s breach-of-contract exclusion applied. The insurer couldn’t hide behind the contract because, legally, the contract didn’t exist.
The Third Circuit judges also tweaked the damages. They zeroed out Molbert’s 25% fault allocation entirely. Why? Because the contractor’s unlicensed status was the primary driver of the defect. They also bumped up her mental anguish award. The final tally settled at $448,431.34. Travelers still won a partial victory: their policy didn’t cover the cost of replacing the bulkhead itself, nor the mental anguish damages. But the house damage? That’s covered under the products-completed operations hazard provision.
Molbert’s case is now a textbook example of how a cheap, unlicensed job can spiral into a six-figure liability for insurers and contractors. The ruling stands as a warning to riverfront owners: check the license before you check the price. The next step isn’t clear, but with the appellate decision final on the liability question, attention turns to whether Travelers will pay the remaining balance voluntarily or if this heads back to the trial court for enforcement.