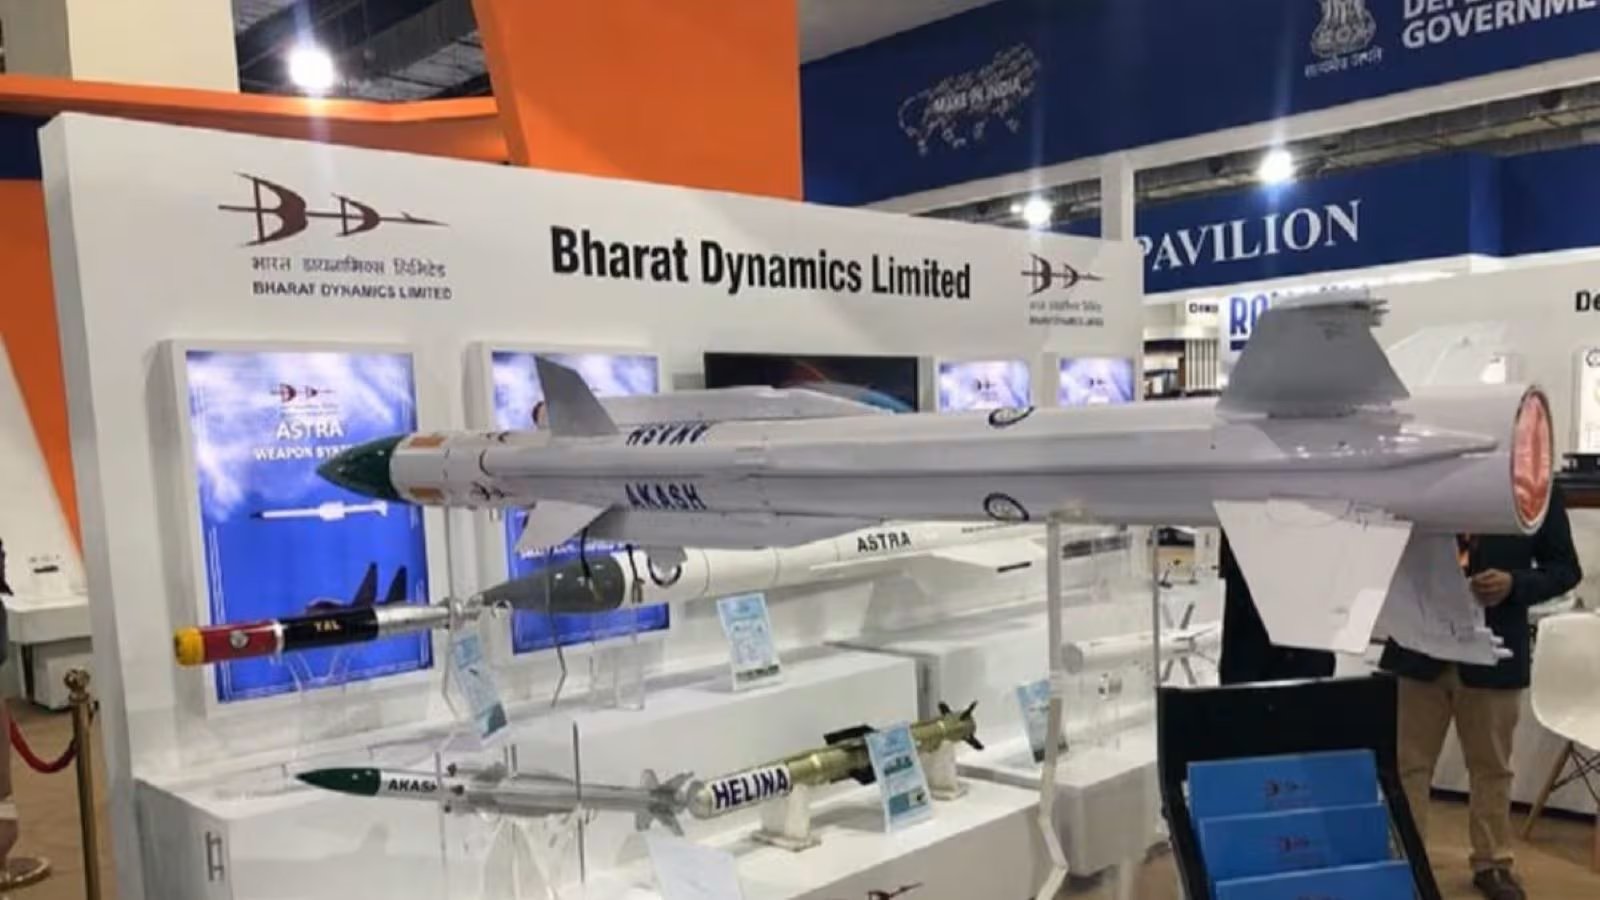
Shares of Bharat Dynamics Ltd closed 0.76% lower at ₹1,162 on the BSE after the company released its Q4 results and announced the ₹810.79 crore MoD deal.
The filing shows net profit of ₹118.8 crore for the quarter ended 30 June 2026, a 600% jump from ₹18.4 crore a year earlier. Revenue rose to ₹572.2 crore, more than double the ₹247.9 crore earned in the same period last year, while EBITDA turned positive at ₹83.1 crore, up from a loss of ₹45.4 crore. The EBITDA margin settled at 14.5%, a sharp improvement over the previous year’s negative margin.
The ₹810.79 crore contract, signed on 23 September, covers 160 Satellite Smart Anti‑Airfield Weapon systems for the Indian Air Force. The SAT‑SAAW kit is 60% indigenous and will be delivered in phases across 2027‑28 and 2028‑29. This deal adds to a burgeoning order book that already includes a ₹1,347.71 crore agreement with Hindustan Aeronautics Ltd for launchers and countermeasure dispensing systems, slated for 24‑60 month execution.
Analyst Rakesh Gupta of DEFIBank remarked, "The new MoD contract cements Bharat Dynamics’ position as a preferred supplier and should translate into steady cash‑flow generation.” He noted that the company’s order pipeline is now firmly in the ₹10 billion bracket for the next fiscal year.
Looking ahead, Bharat Dynamics has not yet issued formal guidance for FY27, but the company’s board is expected to review the upcoming defense contracts during the next AGM. The sustained order inflow and improved margins suggest a bullish trajectory, though investors should monitor the timing of deliveries and any potential cost escalations in the 2027‑29 window.