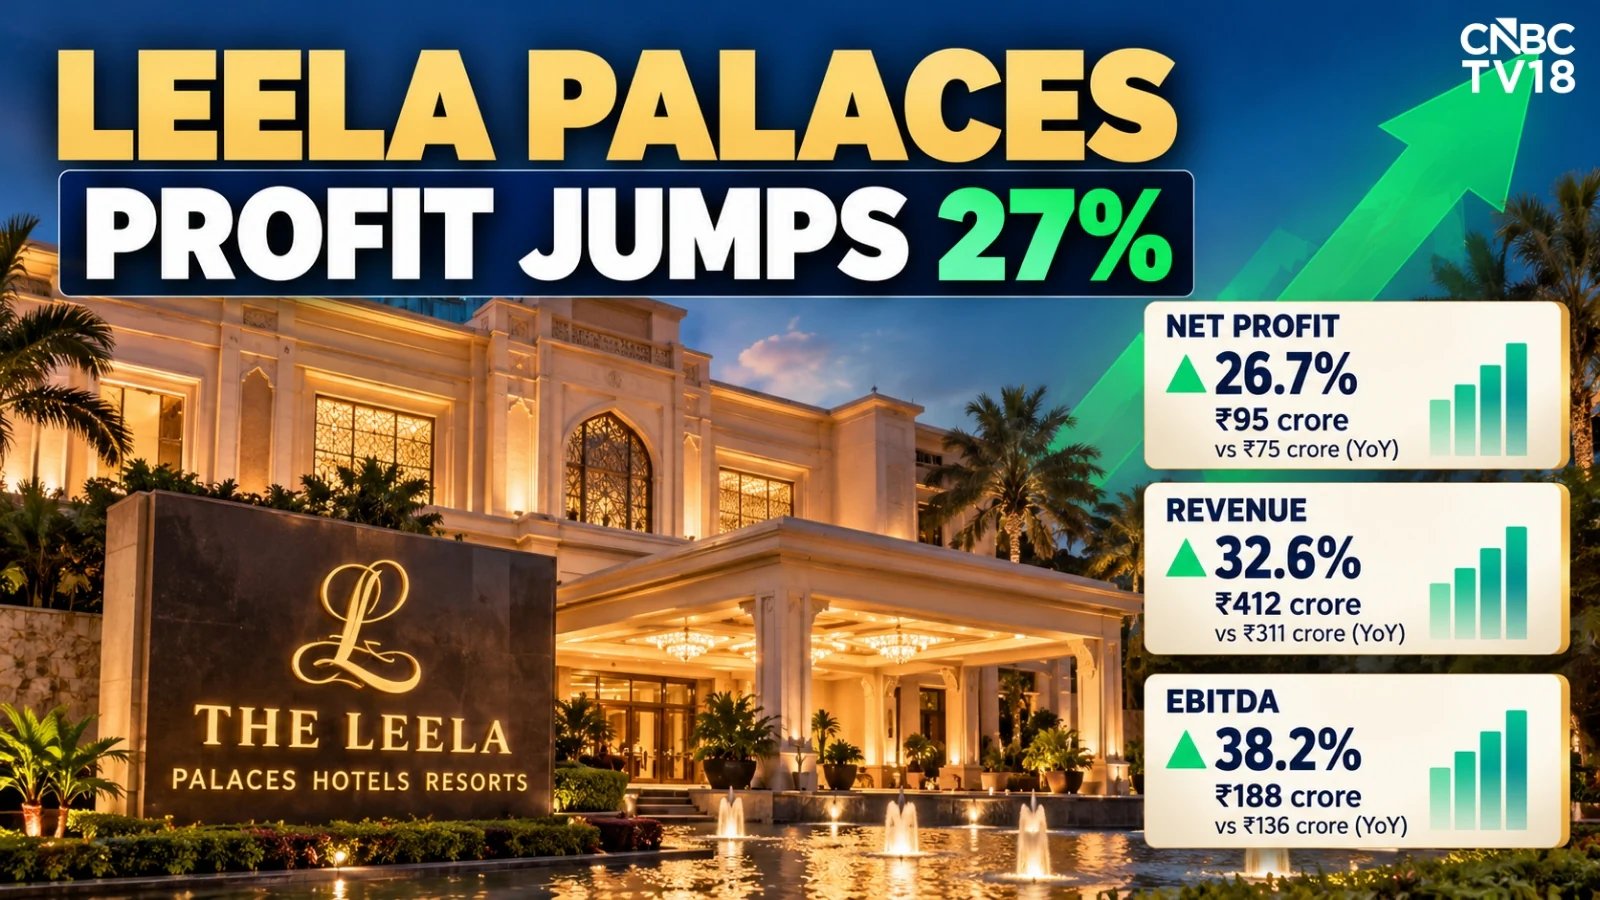
Shares of Leela Palaces fell 2.6% to ₹586.15 after the company announced a 26.7% YoY rise in Q2 net profit to ₹95 crore. The dip follows a 35% rally since January, hinting that traders are pricing in a tightening cycle.
Revenue from operations surged 32.6% YoY to ₹412 crore, up from ₹311 crore a year earlier. EBITDA leapt 38.2% to ₹188 crore, pushing the margin to 45.6% from 43.7% a year ago. The lift is driven by a 30% jump in ADR and a record 30% RevPAR growth, underscoring the brand’s pricing power.
Occupancy held steady at 68.8%, a hair above the 68.7% seen the previous year, while room‑rate revenue climbed 39% to ₹204.1 crore. Food & beverage added 21% to ₹145.6 crore, and hotel‑management fees exploded 76% to ₹28.9 crore, reflecting the ramp‑up of managed properties.
The company’s pipeline of 1,038 keys across 10 properties is on schedule, with the Leela Jaisalmer and the new Luxury Residences in Mumbai slated to open in FY27. Net debt sits at ₹1,215 crore, giving a debt‑to‑EBITDA ratio of 1.4x—improved from 1.6x in March 2026 and a dramatic drop from 3.7x a year earlier.
Analysts note that the 1.4x ratio and a Net Promoter Score of 87 place Leela above the Asia‑Pacific luxury benchmark of 74. While the company hasn’t issued a forward guidance, the steady expansion and improved leverage suggest it will target higher profitability in FY28. Traders will watch next month’s earnings for any shift in the growth trajectory.