Humanity has pulled roughly 222,600 tonnes of gold from the earth across history. Melt it all down, and it forms a single solid cube measuring just 22.6 metres on each side.
Physical gold is finite, concentrated, and increasingly difficult to extract. Modern industrial scale transformed the balance sheet: nearly two-thirds of every ounce ever refined came out of the ground after 1950. As of the third quarter of 2026, total above-ground gold stocks stand at 224,200 tonnes, according to global inventory disclosures. That ledger underpins the modern monetary order.
The breakdown of where that bullion sits explains why institutional markets stay tight.
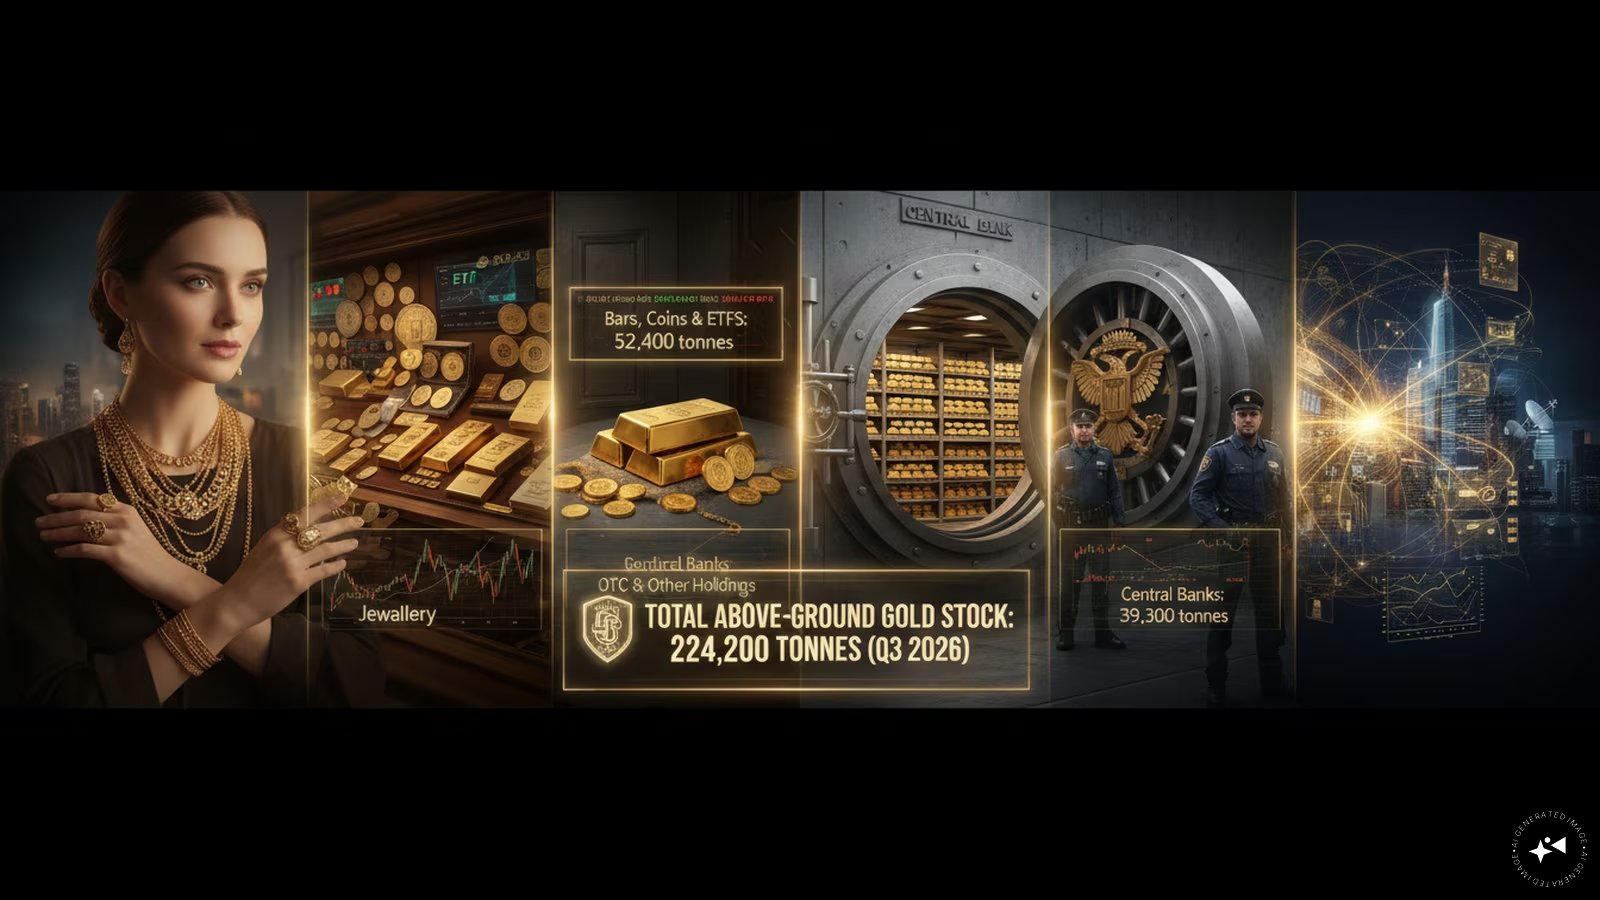
Jewellery still accounts for the undisputed lion's share of circulating physical metal, locking up 98,700 tonnes—or 44% of the global aggregate. Pure investment holdings, comprising physical bars, minted coins, and gold exchange-traded funds, command 52,400 tonnes, or 23% of the world's supply. Central banks hold 39,300 tonnes in sovereign reserve vaults, representing an 18% stake. The remaining 33,800 tonnes, or 15%, sits in over-the-counter contracts and industrial holdings.
| Asset Allocation Segment | Volume (Tonnes) | Share of Above-Ground Stock |
|---|---|---|
| Jewellery | 98,700 | 44% |
| Bars, Coins & ETFs | 52,400 | 23% |
| Central Bank Reserves | 39,300 | 18% |
| OTC & Other Holdings | 33,800 | 15% |
| Total Above-Ground Inventory | 224,200 | 100% |
Sovereign balance sheets treat that 18% share as unencumbered collateral. When liquidity evaporates in paper debt, the physical metal stays put.
Yet the subterranean pipeline is running dry.
Official reserve audits classify approximately 61,000 tonnes of underground deposits as proven reserves—meaning the ore is economically feasible to extract at prevailing production costs. That is the hard ceiling for commercial miners today. Another estimated 114,400 tonnes remain classified strictly as mineral resources: deposits mapped by geologists that lack validated commercial viability.
Converting those 114,400 tonnes into active output will demand deep capital expenditure and advanced extraction technology. Without higher structural price incentives or disruptive extraction chemistry, global mining houses face a fast-approaching wall.