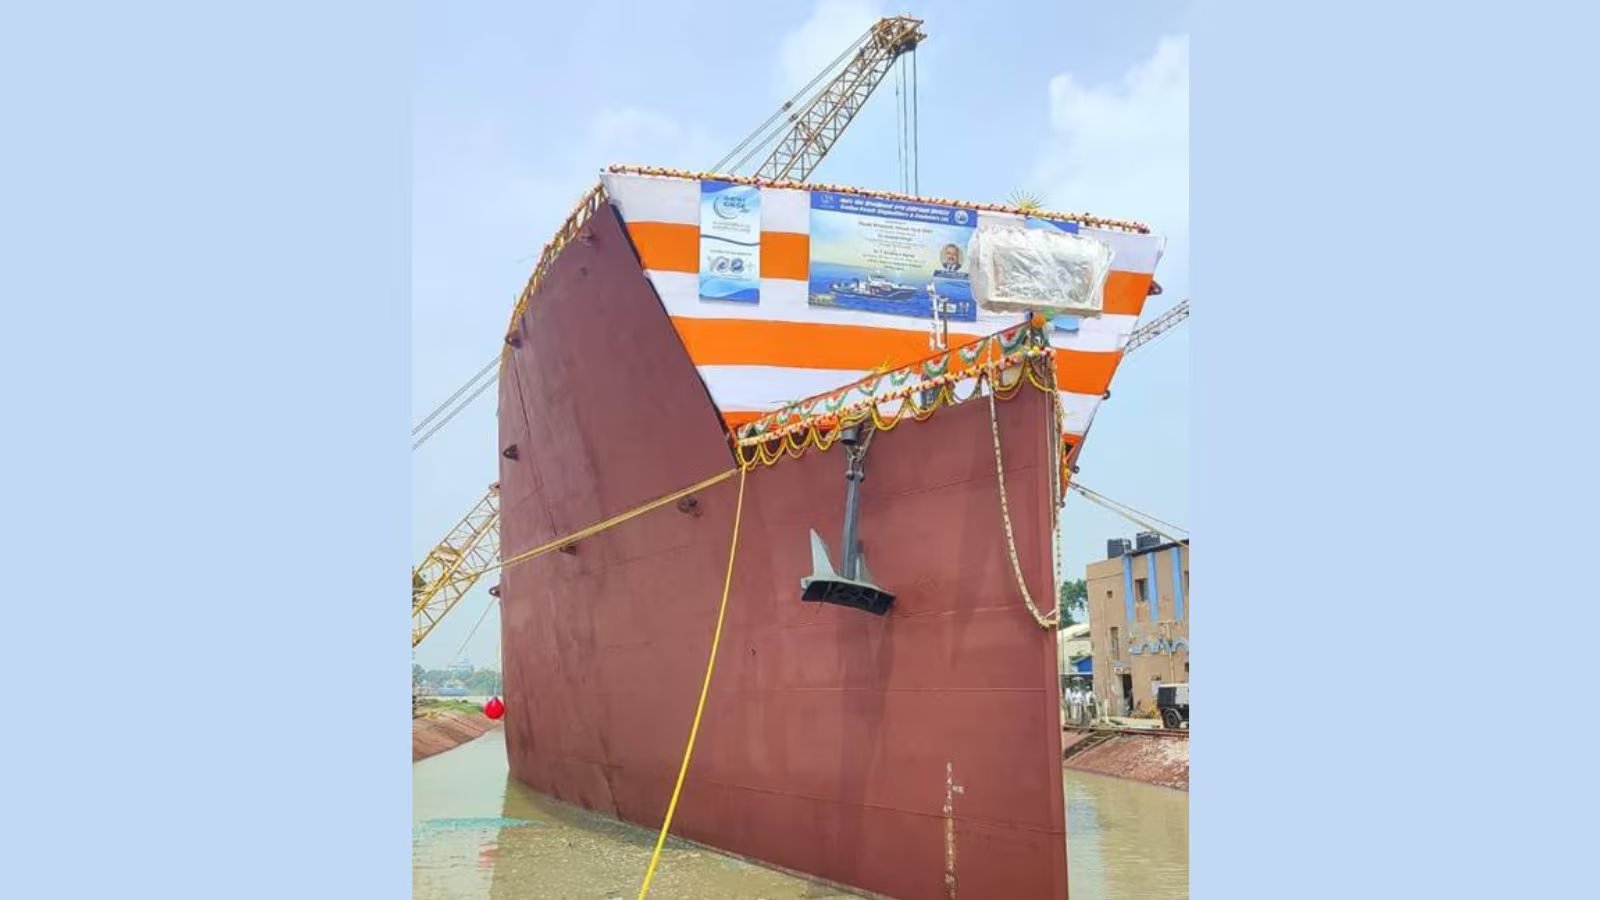
Garden Reach Shipbuilders & Engineers Ltd. shares fell 0.6% to ₹2,212 on Thursday, snapping a three-day winning streak. The reversal followed a bearish brokerage assessment from Goldman Sachs, which reiterated its Sell rating on the state-run defence shipbuilder with a 12-month price target of ₹1,735 per share. The target implies a 22% downside from Wednesday's closing price.
Goldman Sachs pointed to a sharp revenue deceleration post-FY28 as the primary headwind. The brokerage noted that the defence PSU missed operational revenue and earnings per share estimates during the second quarter, even as massive naval contract wins cushion medium-term visibility.
Near-term cash flows remain anchored by a ₹32,000 crore order for Next Generation Corvettes. The contract came in ahead of earlier internal expectations of ₹29,000 crore. Reflecting that order size, Goldman Sachs lifted its earnings per share projections for FY27 by 4% and for FY28 by 6%.
Yet structural concerns loom right after those execution milestones. Deliveries for the P-17A stealth frigate program wrap up in the third quarter. Once that program clears, the company faces an execution vacuum with no major naval deliveries scheduled, which will squeeze operating margins beyond FY27.
No major deliveries are expected after the P
17A ship delivery in the third quarter, highlighting margin concerns post FY27," Goldman Sachs stated in its client note.
Garden Reach reported its second-quarter earnings scorecard on Wednesday, posting operational growth that nevertheless fell short of analyst projections. Profit after tax rose 12.4% year-on-year to ₹172 crore, compared to ₹153 crore in the corresponding period last fiscal year. Revenue from operations climbed 8.9% to ₹1,826.6 crore against ₹1,677 crore a year earlier.
Earnings before interest, taxes, depreciation, and amortisation leaped 25.3% to ₹195.4 crore from ₹156 crore. Operating margins widened by 170 basis points, finishing at 10.7% compared to 9.0% twelve months ago.
| Financial Metric | Q2 FY25 | Q2 FY24 | YoY Growth (%) |
|---|---|---|---|
| Revenue from Operations | ₹1,826.6 Cr | ₹1,677.0 Cr | +8.9% |
| EBITDA | ₹195.4 Cr | ₹156.0 Cr | +25.3% |
| EBITDA Margin | 10.7% | 9.0% | +170 bps |
| Profit After Tax (PAT) | ₹172.0 Cr |
Market Context: The defence public sector undertaking has surrendered significant ground following a furious multi-month rally. At ₹2,212, the counter has corrected 34% from its all-time peak of ₹3,339, leaving the stock down 10% year-to-date.
Street sentiment remains sharply divided over the shipyard's prospects. Out of 11 research analysts tracking Garden Reach Shipbuilders, eight maintain Buy recommendations, one holds a neutral Hold stance, and two advocate an outright Sell.
| ₹153.0 Cr |
| +12.4% |