Premier Energies shares gained 1.57% to close at ₹904 on the National Stock Exchange after the solar equipment manufacturer reported a 30% jump in second-quarter consolidated net profit to ₹458 crore. Top-line expansion drove the bottom-line growth. Revenue from operations climbed 43.3% year-on-year to ₹2,632 crore for the quarter ended September 30, up from ₹1,837 crore in the year-ago period. Total income, which includes other income streams, advanced 38.2% to ₹2,656 crore against ₹1,921 crore in Q2 FY26.
Yet profitability margins tightened across the floor. Operational earnings before interest, taxes, depreciation, and amortisation (EBITDA) increased 31.2% to ₹736 crore from ₹561 crore. But operational EBITDA margin slipped 250 basis points to 28% from 30.5% a year earlier. Profit after tax rose 30.8% to ₹462 crore, yielding a net margin of 17.4% compared with 18.4% twelve months prior. Balance sheet leverage remained contained—the company reported a total debt-to-equity ratio of 0.72 as of September 2026, while the ratio of cash flow from operations to profit after tax touched 0.72 for the first half of the fiscal year.
| Metric (Consolidated) | Q2 FY27 | Q2 FY26 | YoY Change (%) |
|---|---|---|---|
| Revenue from Operations | ₹2,632 cr | ₹1,837 cr | +43.3% |
| Total Income | ₹2,656 cr | ₹1,921 cr | +38.2% |
| Operational EBITDA | ₹736 cr | ₹561 cr | +31.2% |
| EBITDA Margin (%) | 28.0% | 30.5% | -250 bps |
| Net Profit (Reported) | ₹458 cr | ₹353 cr | +30.0% |
| Profit After Tax (PAT) | ₹462 cr | ₹353 cr | +30.8% |
| PAT Margin (%) | 17.4% | 18.4% | -100 bps |
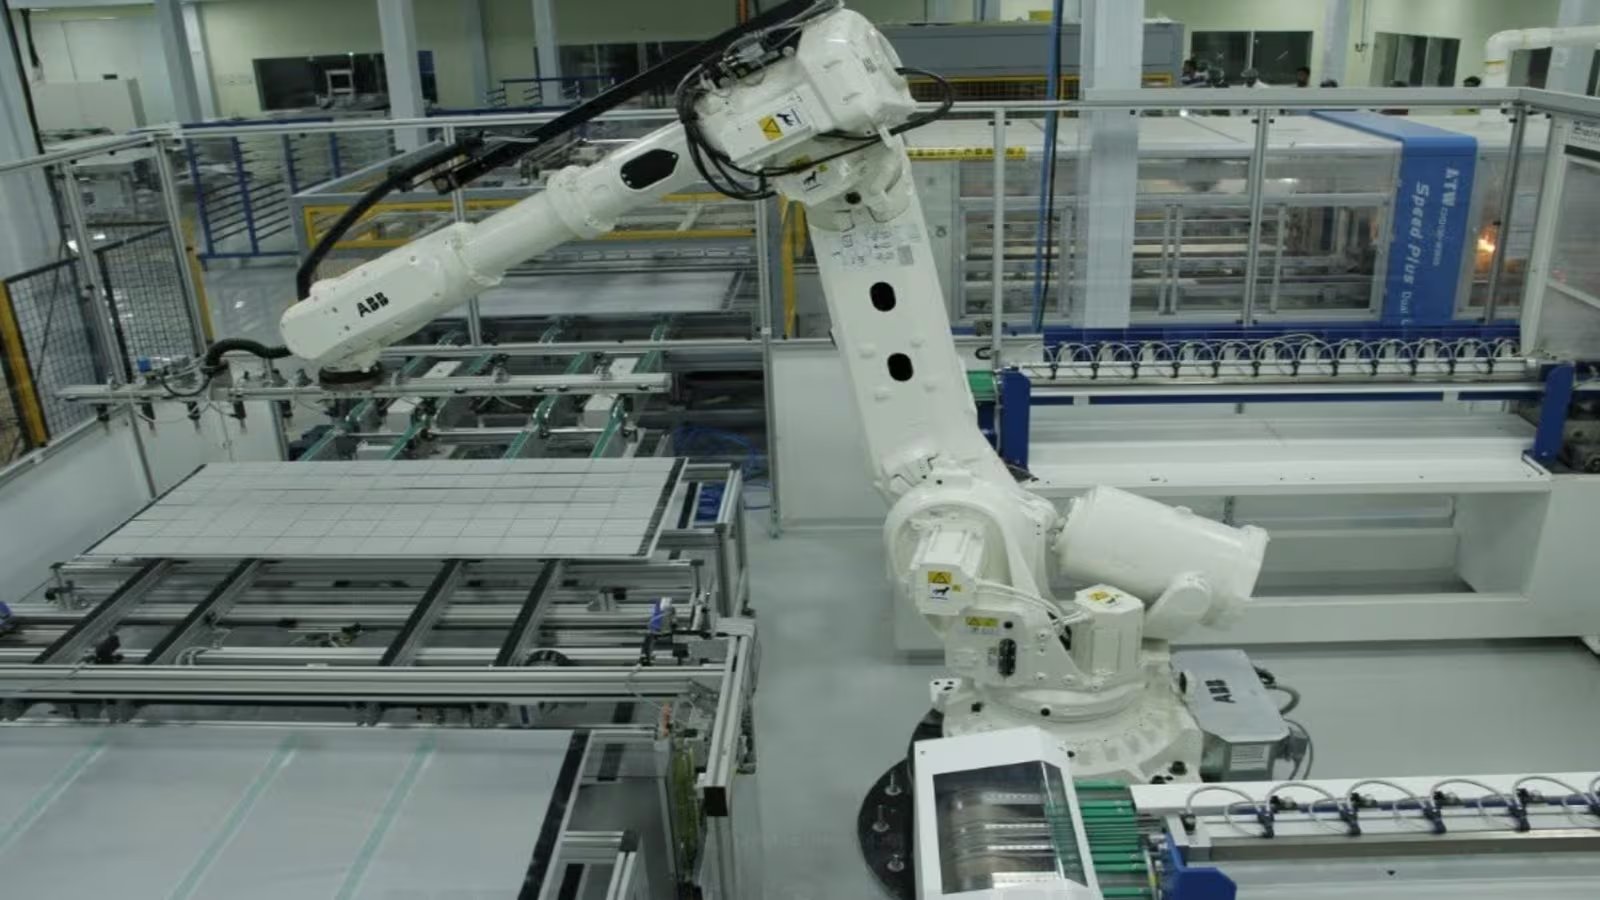
Shop-floor output scaled sharply. Premier Energies produced 916 megawatts of solar cells and 1,199 megawatts of modules during the three-month period. That output ran against an operational manufacturing base of 10.6 gigawatts in solar cells and 11.1 gigawatts in modules. Demand visibility stretches across multiple quarters. The company closed September with an unexecuted order book of 10,729 megawatts valued at approximately ₹16,600 crore.
Domestic utility contracts dominate the book. Indian buyers account for 99% of total contract value, leaving export orders at just 1%. Product allocation sits evenly split: solar modules and solar cells each comprise 48% of the order pipeline by value. Transformers make up 2%, while engineering, procurement, and construction contracts contribute the final 1%.
Capital expenditure now pivots toward integrated upstream production. According to regulatory disclosures, a 7-gigawatt solar cell facility will begin commercial production shortly, rolling out N-type TOPCon G12R cells designed for an average efficiency rating of 25.8%. Parallel work continues on ancillary units. The initial phase of a 6-gigawatt-hour battery energy storage system is scheduled for commissioning in July 2027, followed by an aluminium frames facility in September 2027. For its planned 10-gigawatt ingot-wafer project, Premier Energies completed site land acquisition, started ground preparation, and placed advance machinery orders for phase one.