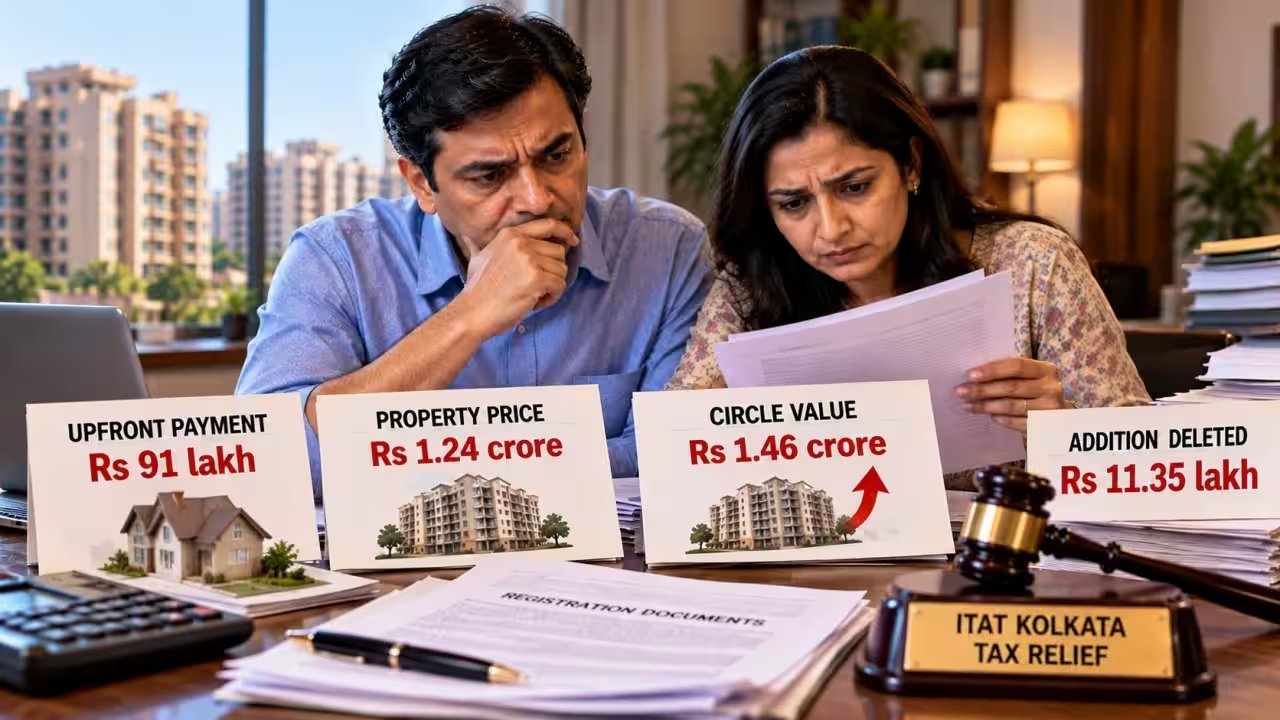
ITAT Kolkata scrapped a ₹11.35‑lakh tax addition to a homebuyer’s taxable income after the property’s stamp duty value climbed from ₹1.23 crore to ₹1.462 crore in September 2023. The buyer had signed a registered agreement on 22 January 2021, paying ₹91 lakh through banking channels before the agreement date, and the conveyance deed was executed in September 2023 without altering the purchase price.
But the Assessing Officer had applied the higher September 2023 circle rate, treating the ₹22.71‑lakh difference as a benefit under Section 56(2)(x) and adding half that amount—₹11.35 lakh—to the buyer’s income. The tax tribunal rejected the CIT(A)’s March 2026 order that upheld the addition.
Yet the ITAT found that the buyer could invoke the provisos to Section 56(2)(x) because the agreement date, not the registration date, set the purchase consideration. CA Suresh Surana, representing the buyer, noted, "The agreed price was consistent with the circle rate applicable at the time, and a sizeable advance had already been paid through banking channels."
The tribunal held that the 2021 circle rate should govern the transaction, citing the law’s safeguard against rising valuations between agreement and registration. By overturning the additional tax, the ITAT affirmed that buyers who honour their agreements early and pay through prescribed channels need not face penalties for later market hikes.
The decision is poised to influence future assessments of property transactions where registration lags behind the binding agreement, potentially easing the tax burden on a growing number of homebuyers across India.