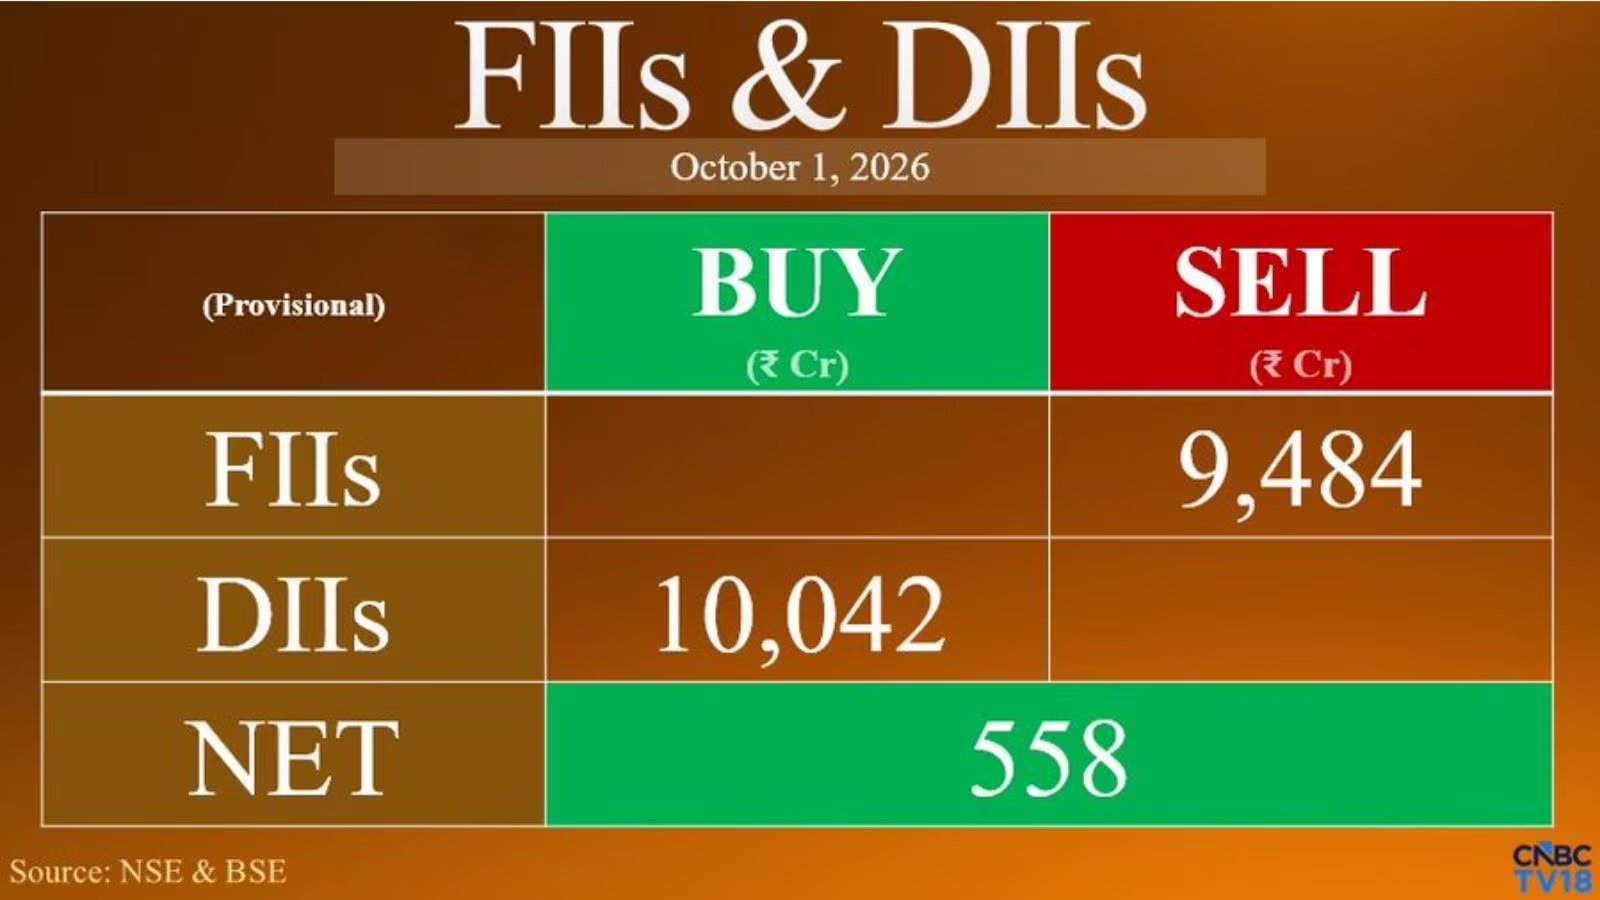
FIIs offloaded a record ₹34,966 crore across four trading sessions, with daily net sales of ₹5,353 crore on September 28, ₹9,980 crore on September 29, ₹10,148 crore on September 30 and ₹9,484 crore on October 1.
Domestic institutional investors (DIIs) countered the sell‑off, injecting ₹10,042 crore on October 1 after adding ₹5,189 crore on September 28, ₹6,953 crore on September 29 and ₹11,272 crore on September 30, bringing four‑day net purchases to ₹33,455 crore.
The indices mirrored the FII activity: Nifty closed 571 points lower at 22,422, down 3% for the week, while the Sensex slipped 571 points to 71,910, its fourth consecutive loss this week. The Nifty Bank index fell 2%, and the Midcap index dropped almost 4%, eroding roughly ₹20 lakh crore in market value.
Sectoral fallout was uneven. Hospitality and auto led the decline, with the auto index down over 3% for the week; Bajaj Auto plunged 8% after weaker‑than‑expected sales, and Maruti Suzuki followed suit despite sales near expectations. IT bucked the trend, posting a modest gain.
Market breadth stayed weak, with roughly one stock advancing for every three that fell. The rupee weakened to 96.48 against the dollar, its largest one‑day drop in two months, adding further pressure on domestic equities.
Looking ahead, analysts expect the market to test support near the 22,400 level as FIIs reassess risk appetite. Upcoming earnings from major IT and pharma firms in early November could provide a short‑term catalyst, while RBI’s policy meeting in mid‑October may influence liquidity and investor sentiment.