15,214 tractors left the showroom shelves in September 2026, a 16.7% dip from a year earlier. The fall is a mix of timing—GST cuts earlier this year, the festive calendar shifting into October, patchy monsoon rains, and a slower Kharif sowing season.
August, however, told a different story: 10,072 units sold, up 19.1% YoY. Domestic sales leapt 20.5% to 9,523, while exports barely moved, down 0.9% to 549. The dip in September came after a surge, hinting at a seasonal swing.
Yet the first half of FY27 still looks solid. From April to September, Escorts Kubota moved 70,879 tractors, 10% more than the 64,458 sold in the same stretch last year. Domestic volume rose 11.3% to 68,085, showing rural demand is holding.
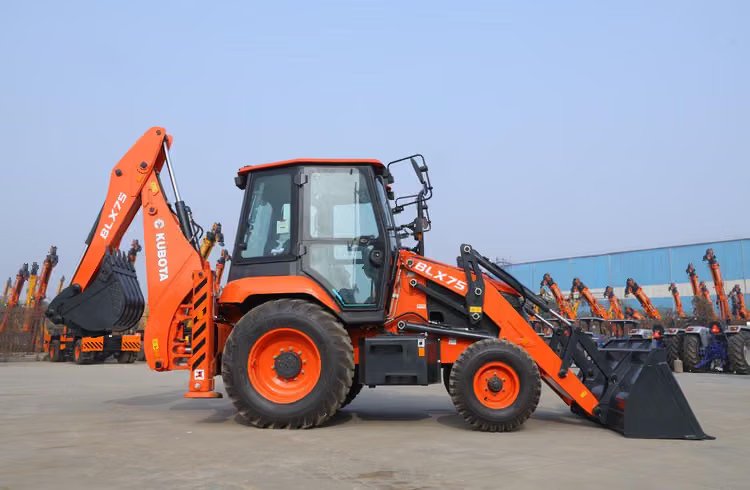
Construction equipment tells a different tale. September sales jumped 92.5% YoY to 795 machines, up from 435 in August. These machines, driven by government infrastructure pushes and mining, signal a robust demand side for heavy gear.
Behind the numbers are policy shifts. The GST rate cut in September 2025 created a high base, making this year's figures appear lower. Coupled with the monsoon lag and the move of the harvest calendar, the market’s rhythm is in flux.
For buyers, the takeaway is simple: keep an eye on the next quarter. Festive demand, harvesting schedules, and improved monsoon patterns could revive sales, while export markets may recover as geopolitical uncertainties ease.