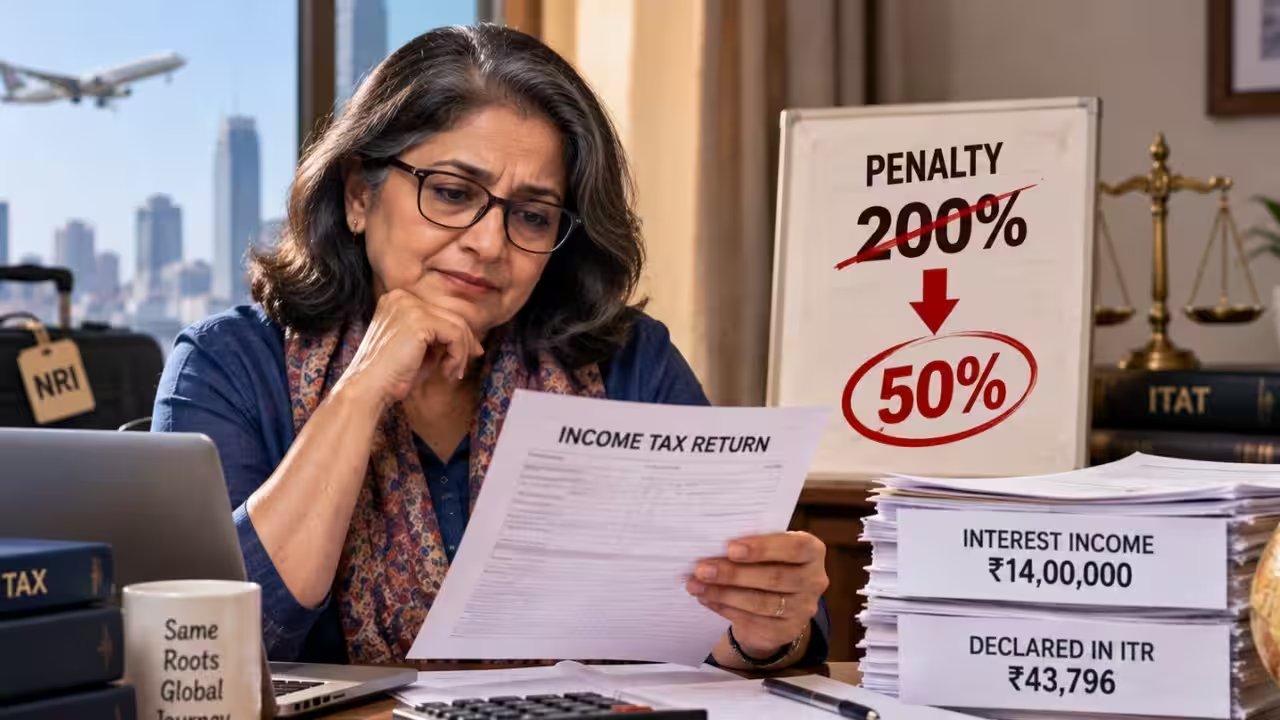
A 57‑year‑old non‑resident Indian woman filed her 2020‑21 tax return with a gross income of just Rs 43,796 while the tax department uncovered an undisclosed interest of Rs 14,02,321. The omission triggered a 200% penalty, amounting to Rs 4,85,178, under Section 270A. She had no prior history of non‑compliance and claimed the oversight was inadvertent.
The Commissioner of Income Tax, Ahmedabad, upheld the penalty after reviewing the notices, noting the taxpayer had failed to disclose the interest and had not responded to multiple electronic notices. The CIT(A) concluded that the omission constituted mis‑reporting, which, under the law, attracts the higher 200% rate.
In a hearing before the Income Tax Appellate Tribunal, Mumbai, the tribunal agreed the penalty was warranted but ruled that the circumstances did not prove deliberate mis‑reporting. It therefore reduced the applicable rate from 200% to 50%, maintaining the penalty at Rs 2,42,590. The tribunal stressed that mere non‑compliance with notices does not automatically equate to intentional under‑reporting.
The taxpayer’s counsel, Anuj Dave, explained that she had been living abroad and had relied on an accountant who failed to notify her of the notices. Dave highlighted that she paid Rs 5,49,410 in tax and interest after learning of the shortfall, citing this as evidence of good faith. He argued that the 200% penalty was disproportionate given her circumstances.
The tribunal’s decision leaves the penalty of Rs 2,42,590 unpaid, and the taxpayer must settle it by March 2026, after which the case will close.