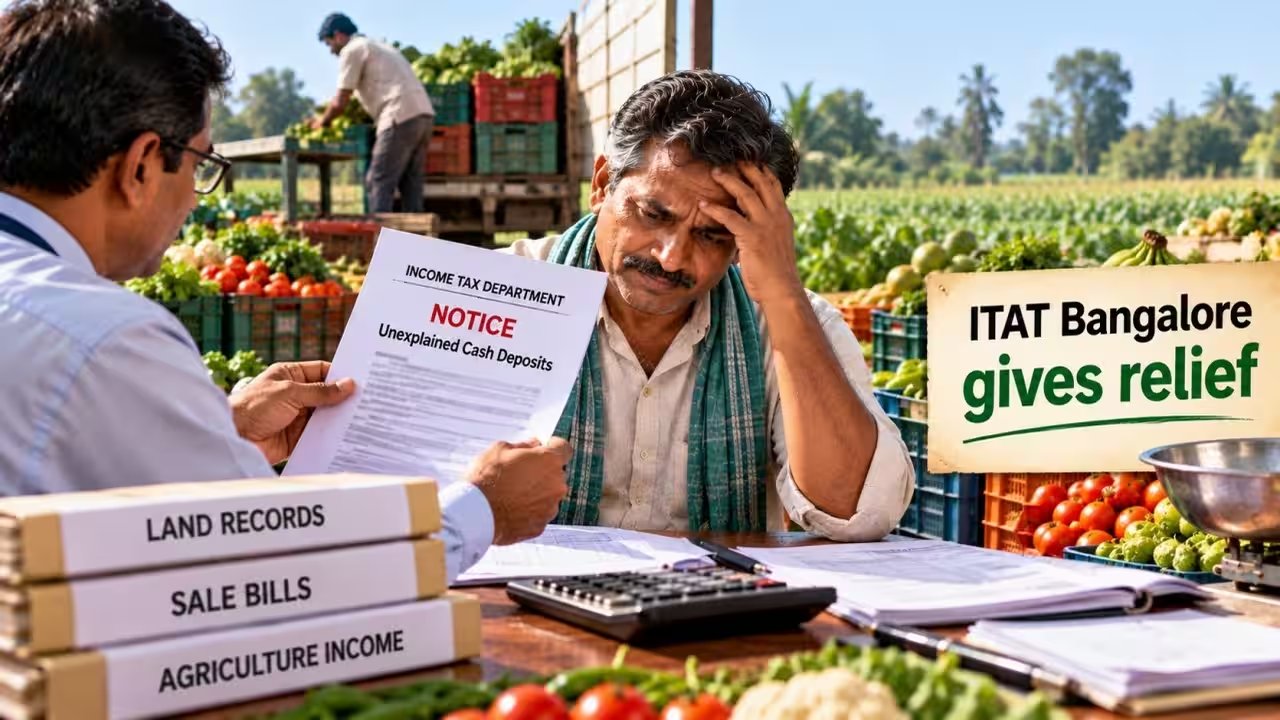
Ramachandrababu, a vegetable and fruit grower from Bengaluru, had been hit with a tax notice after depositing hefty cash sums into his bank account in 2024. The notice, issued by the Income Tax Department, alleged that the deposits were unexplained cash credit under Section 69, citing a mismatch between the amounts and his filed ITR.
He countered by presenting land records, APMC sale bills and bank statements, claiming the money was earned from cash sales to the APMC yard. The AO dismissed the explanation, noting missing cultivation‑related expenses and an absence of agricultural income in prior filings.
On 28 August 2026, the ITAT Bangalore overturned the decision. Chief Justice Ajay Kumar noted that the RTC and Pahani records confirmed land ownership but did not detail crops, and that the lack of formal purchase records is reasonable for small‑scale farmers. He accepted the farmer’s documentation as sufficient proof of agricultural origin.
Akhil Chandna, partner at Grant Thornton Bharat, highlighted that the tribunal’s ruling underscored the need for the Income Tax Department to verify claims rather than rely solely on documentation gaps. The ruling is expected to prompt a review of how rural farmers are audited in future.
The farmer’s wife, Meera, expressed relief, saying, "The tribunal understood our reality; we are not big businessmen, we just grow and sell in the market."
The case sets a precedent for other small farmers facing similar notices, and the Income Tax Department is expected to issue guidance on clarifying agricultural income disclosures by 15 September 2026.