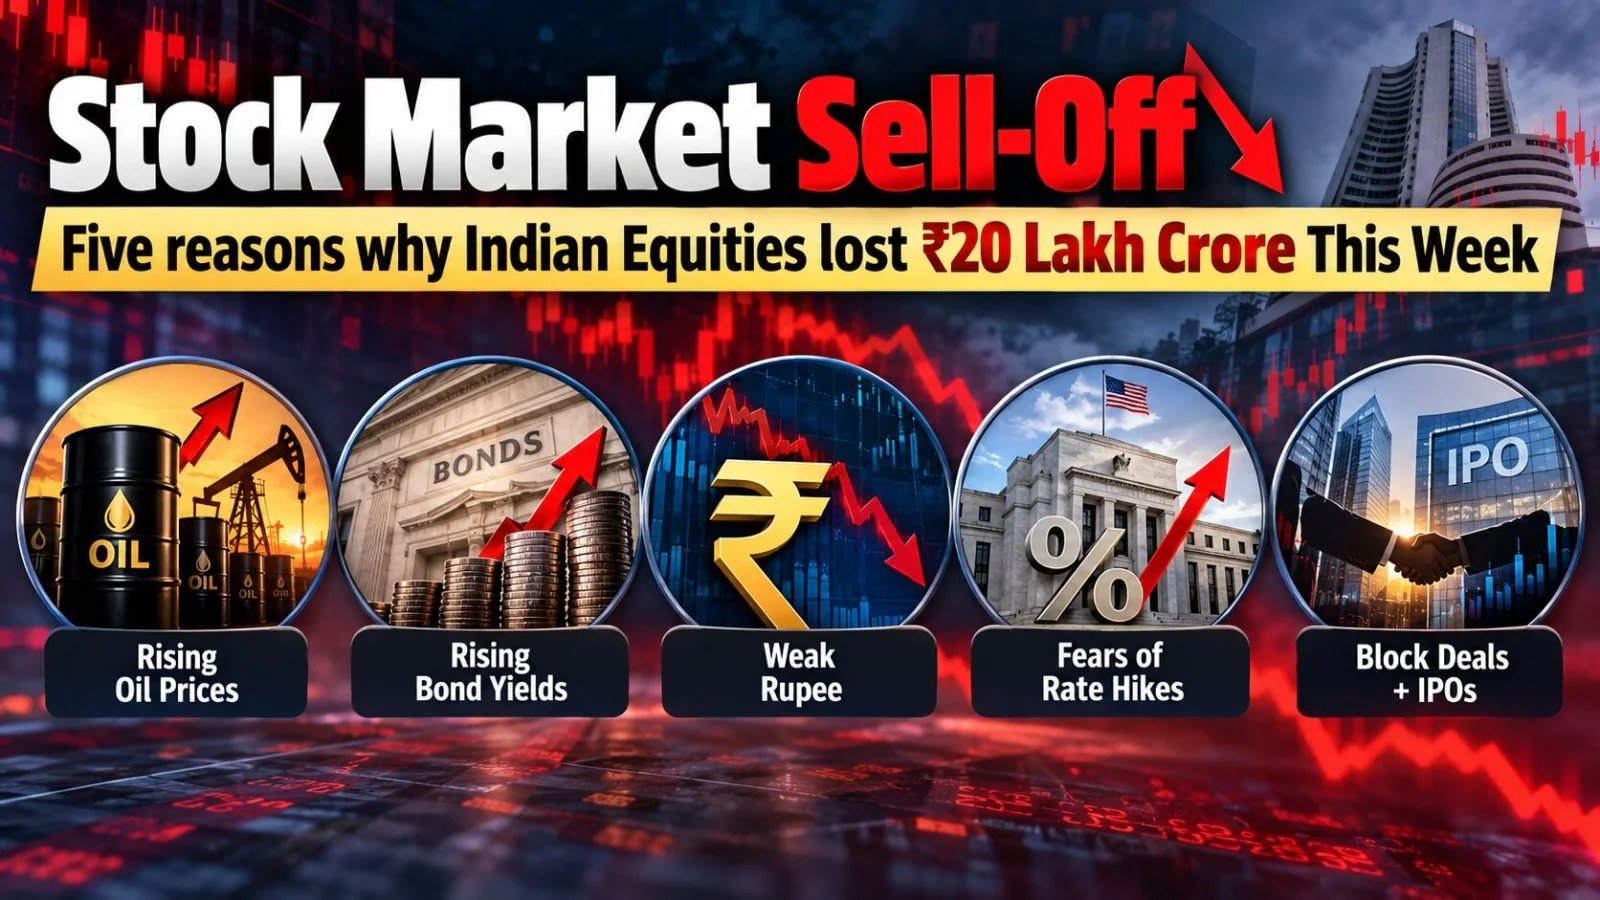
The bleeding continued on Thursday, October 1, capping off a brutal week for Indian equities. The BSE saw a collective wipeout of ₹20 lakh crore in market value. This isn't just a bad week; it's a structural break. The Nifty 50 has now posted negative returns for eight straight weeks—a streak not seen in a quarter-century. Twelve heavyweight stocks, including Reliance Industries, Maruti Suzuki, and HUL, are stuck at 52-week lows. The damage is broad, deep, and accelerating.
Crude oil is the primary villain here. Brent crude for December contracts has snapped back to $100 a barrel, up from the $96–$97 range seen earlier. This energy spike is dragging global bond yields higher. The US 10-year yield sits at 5.3%, with the 30-year yield flirting with 5.7%. For Indian markets, rising global rates make domestic assets less attractive, triggering capital outflows.
Foreign Institutional Investors (FIIs) have been relentless sellers. They’ve dumped nearly ₹2.5 lakh crore in the cash market this year. The trend reversed sharply in September, where selling hit over ₹36,000 crore, reversing the inflows seen in July and August. This exodus has weakened the currency. The rupee crossed 96 against the US dollar for the first time in two months, adding import cost pressures and volatility.
Supply-side shocks are compounding the demand-side weakness. Nearly 100 mainboard IPOs have raised ₹1.13 lakh crore so far this year, soaking up liquidity. Block deals worth close to ₹1 lakh crore in the first nine months have further drained cash from the system. This is nearly matching the total volume of the entire previous year. The market simply doesn’t have enough new money to absorb this volume.
The outlook remains murky. With the Federal Reserve already hiking rates, the spotlight is now on the Reserve Bank of India. Markets expect the RBI to raise rates in its upcoming policy decision. If the Fed follows with one or two more hikes by year-end, the global monetary tightening cycle could squeeze liquidity further. Traders should brace for continued volatility as these macro headwinds collide with heavy domestic supply.