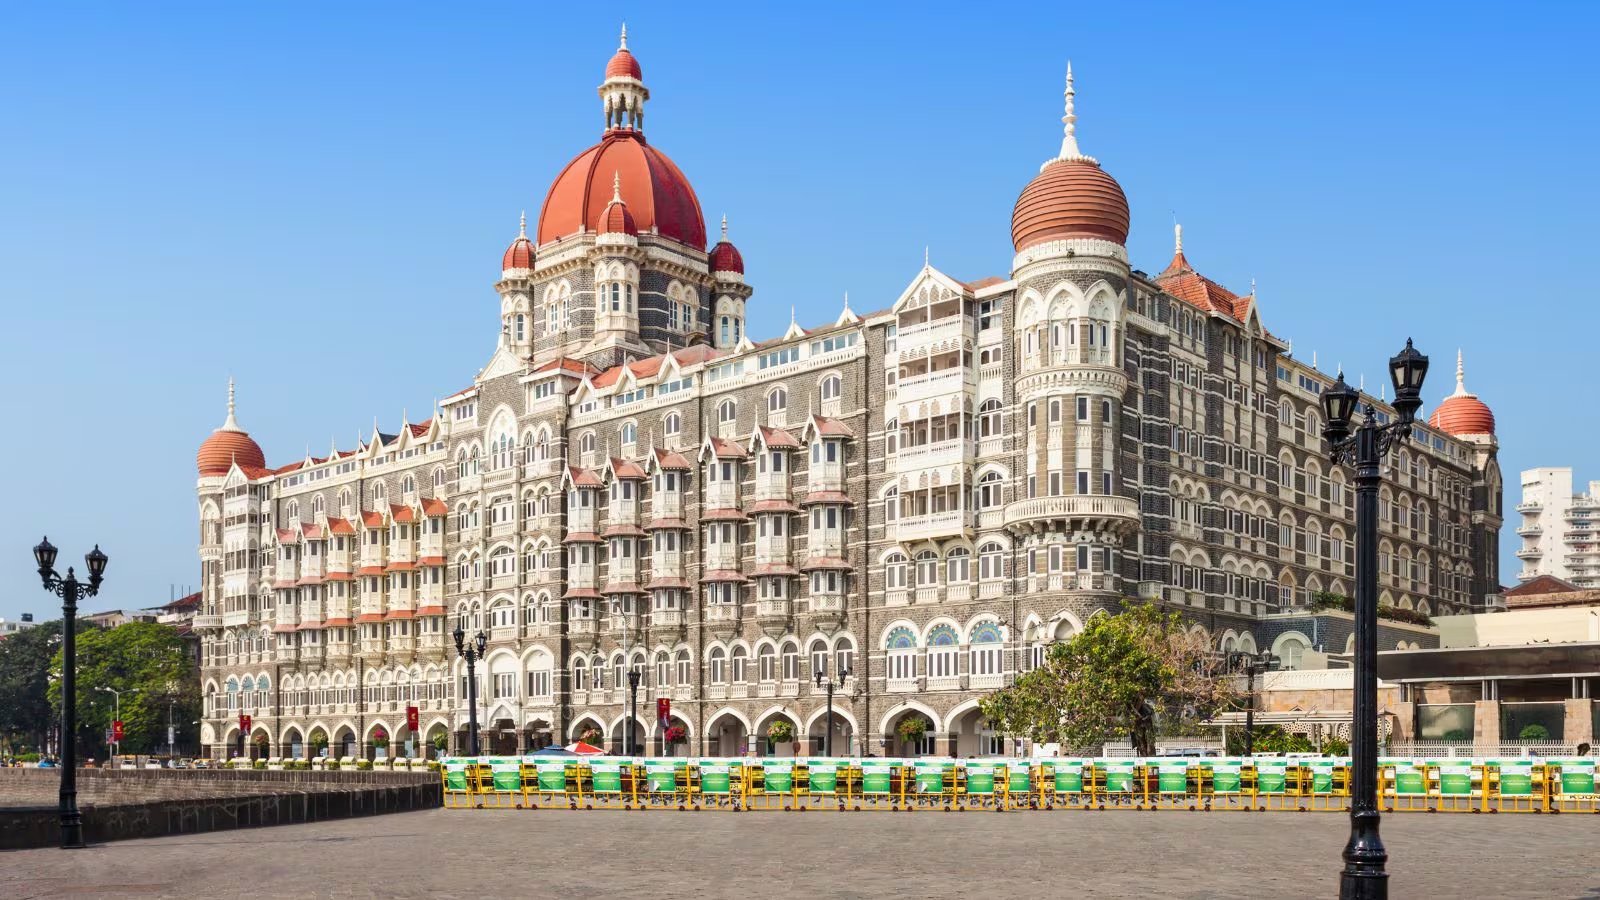
Indian Hotels Company Limited (IHCL) reported Q2 revenue up 22% YoY and EBITDA up 24% YoY, both surpassing consensus by 5% and 3% respectively. Shares climbed 5.5% to ₹794.65, a fresh 52‑week high.
The company lifted its full‑year revenue growth outlook to 15‑17% from the previous 12‑14% and now anticipates mid‑high‑teen EBITDA growth for FY27 and FY28.
Room‑rate revenue grew 25% across the portfolio, 28% for the Taj brand and 25% overall. IHCL plans 50 new openings in FY27, with 30 slated for the second half, and aims to reach 400 operational hotels by Q3 FY27. Ginger’s revenue rose 25% to ₹193 crore, management fee jumped 25% to ₹156 crore, while cash reserves stood at ₹4,369 crore.
Among the 31 analysts covering IHCL, 25 hold a buy rating and five a hold. Nomura retains a buy, targeting ₹850 per share—implying a 12.9% upside—after noting the company’s 22% revenue and 24% EBITDA gains. The rating is bolstered by the upgraded outlook and the brand’s expansion plans.
IHCL is positioned to capture inorganic opportunities and benefit from the BRICS Summit’s boost to the Q2 numbers, as CEO Puneet Chhatwal noted. The next earnings release is scheduled for May 29, 2026, when investors will gauge whether the guidance holds amid rising operating costs and competitive pressure.