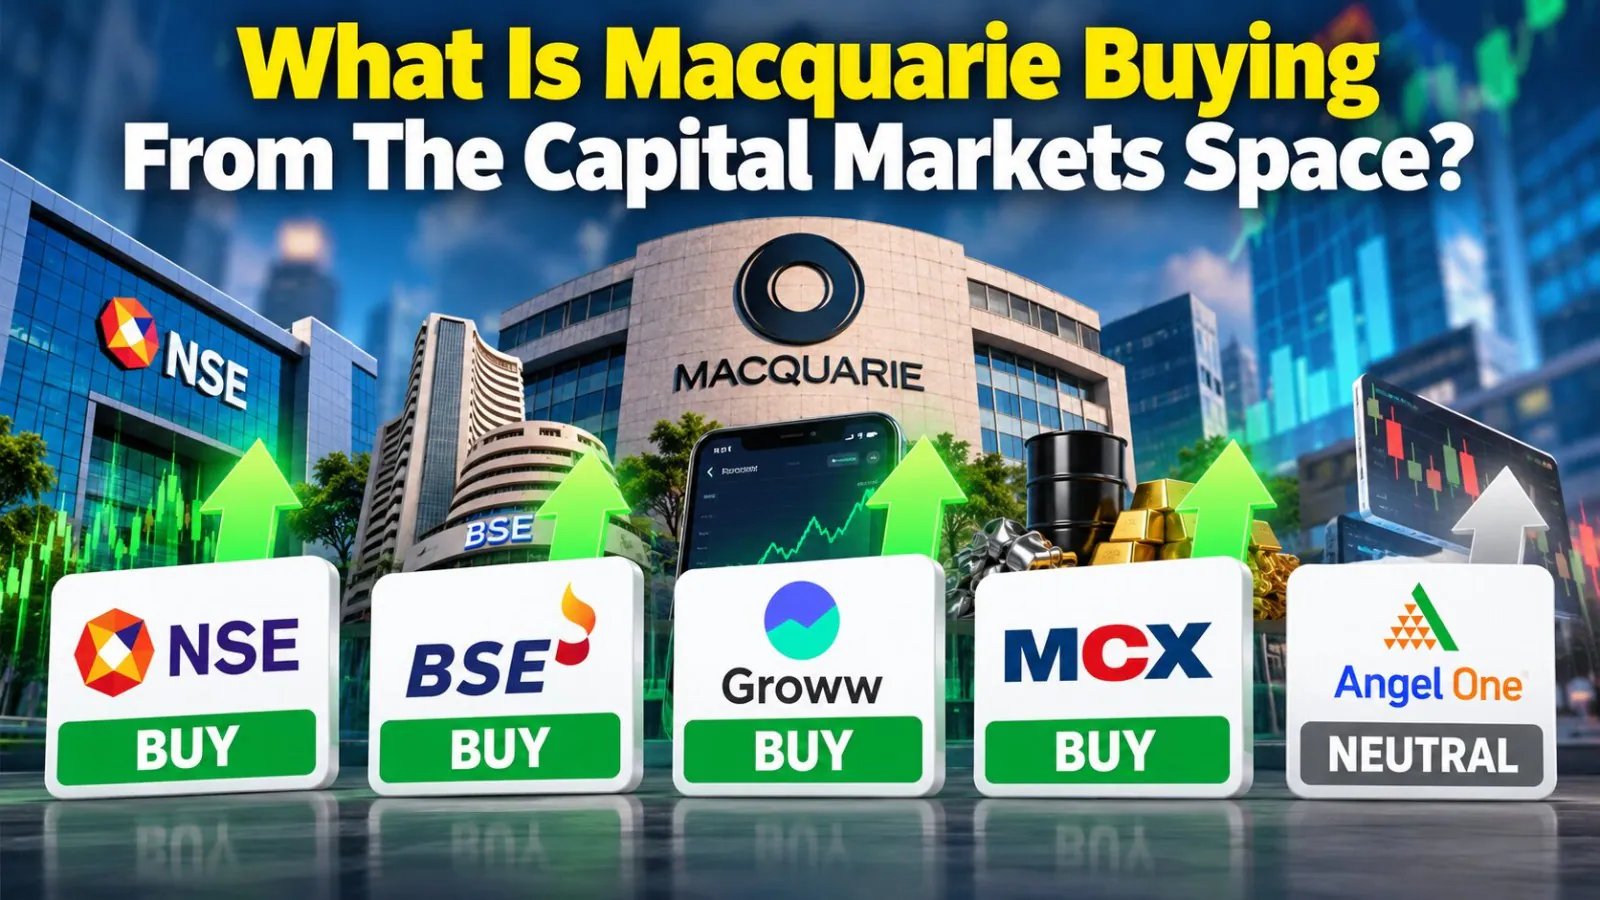
Macquarie’s coverage of Groww, the parent of the Groww trading app, kicked off with an outperform call and a ₹260 price target, signalling a 39% upside from the stock’s current price.
The platform’s market‑cap is now ₹21.4 billion, and shares have climbed 21% since the IPO, leaving a ₹260 target well above the ₹210 issue price.
In the same suite of new coverage, Macquarie awarded the National Stock Exchange an outperform rating with a ₹1,965 target (≈11% upside), the Bombay Stock Exchange a 22% upside target of ₹4,000, and MCX a 11% upside target of ₹3,820. Angel One received a neutral rating and a ₹285 target, implying a 5% downside.
Groww’s 39% upside stands out because its platform‑centric model creates a flywheel of user acquisition, higher margin trading fees, and robust cash generation—metrics that Macquarie highlighted as key drivers of future earnings growth.
Sector‑wide, the capital‑market space is tightening as BSE’s pivot to index options and MCX’s commodity dominance grow. Analysts note that platform players like Groww can capitalize on low penetration and high product elasticity, but will need to fend off competitive pressure from established brokerages.
Looking ahead, Macquarie expects Groww to expand its fee‑based revenue, deepen its retail user base, and maintain a margin expansion trajectory that could sustain the 39% upside until the next earnings cycle. Investors should watch for quarterly guidance on fee‑income growth and any regulatory changes that could impact brokerage commissions.