Shares of Premier Energies Ltd. closed at ₹895 on the BSE, a gain of ₹9 or 1.02%—a modest lift on a day when the company disclosed a ₹4,001‑crore order book for the July‑September quarter.
The order book, worth 2,308 MW of solar cell and module supplies, dwarfs the company’s 2025‑26 revenue and gives a clear revenue trajectory for FY27‑28. Managing Director Chiranjeev Saluja said the influx validates the firm’s growth strategy and execution, highlighting demand for scale, bankability and cutting‑edge technology.
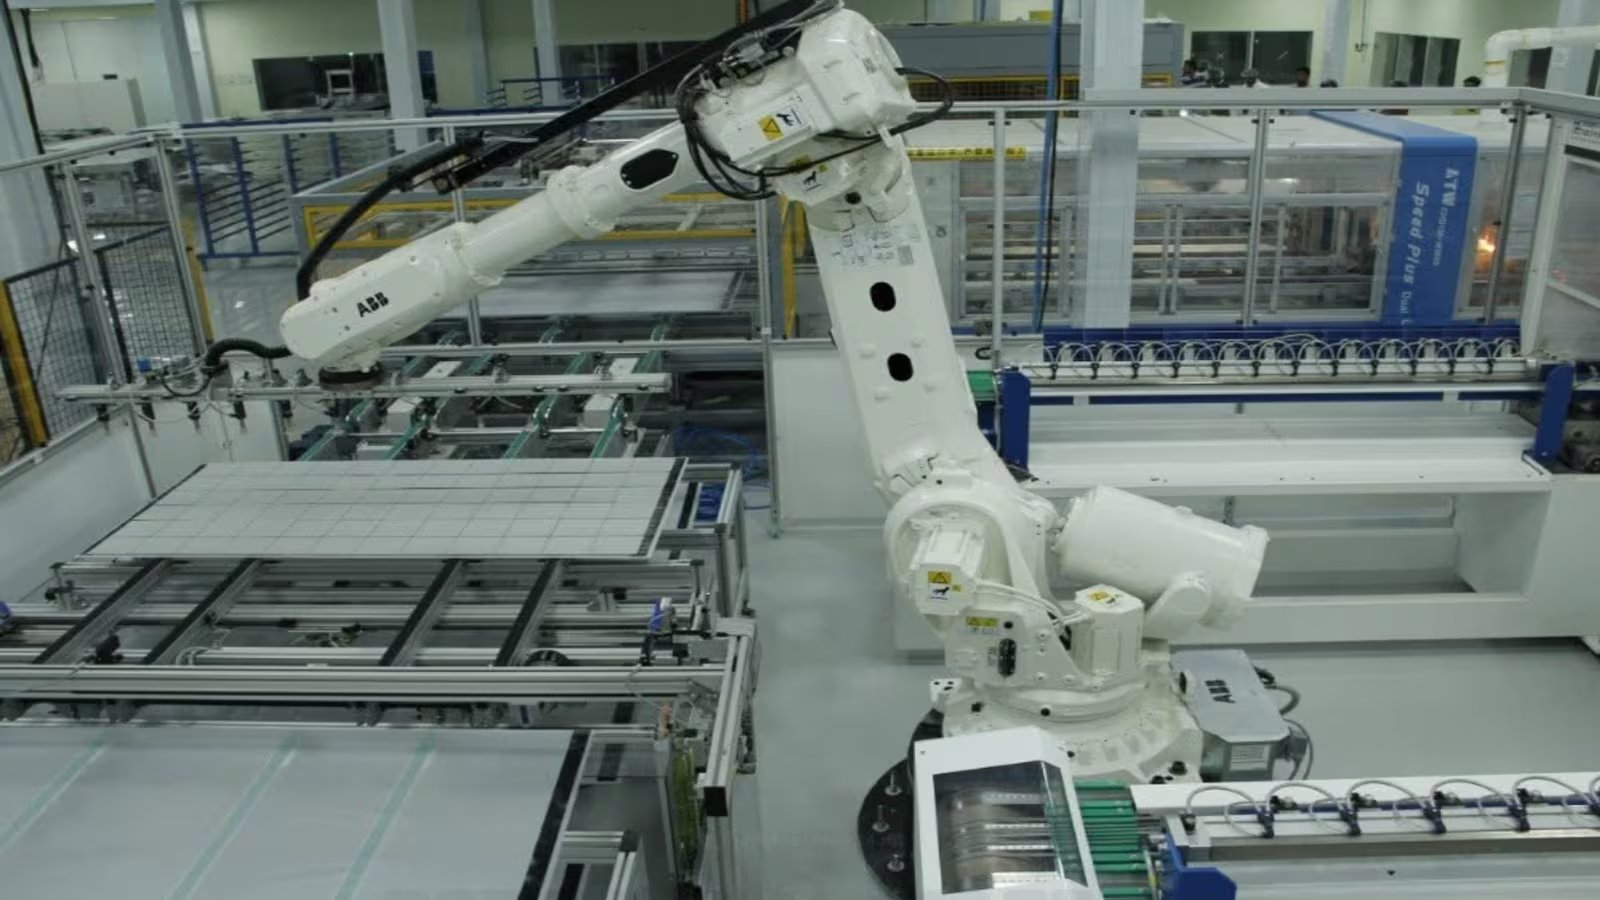
Premier’s manufacturing footprint has nearly tripled: module capacity now sits at 11.1 GW, up from 3.6 GW, while solar‑cell capacity jumps to 10.6 GW from 3.6 GW. The 7‑GW tunnel‑oxide passivated‑contact plant at Naidupeta, commissioned last month, underpins the cell expansion.
Chief Business Officer Vinay Rustagi noted that the order book is almost twice the 2025‑26 revenue, providing line‑of‑sight on margins into FY28. He also flagged new growth levers: European exports and battery‑energy‑storage systems. Europe’s non‑China solar market could grow from 5‑7 GW next year to nearly 30 GW by 2030, while the domestic BESS market may reach 40 GWh and ₹40,000 crore annually.
The company’s module capacity now exceeds current demand by about 250 GW, pushing margins toward zero in that segment, whereas cell capacity remains 32 GW against a supply of 22 GW—keeping pricing and margins firm. This differential is a key factor in the firm’s margin outlook.
Analysts track Premier’s FY27‑28 guidance, expecting margin visibility on the back of the robust order book. The market reaction—shares climbing 1.02%—reflects confidence in the trajectory, though investors remain cautious as the company scales up to meet future demand.