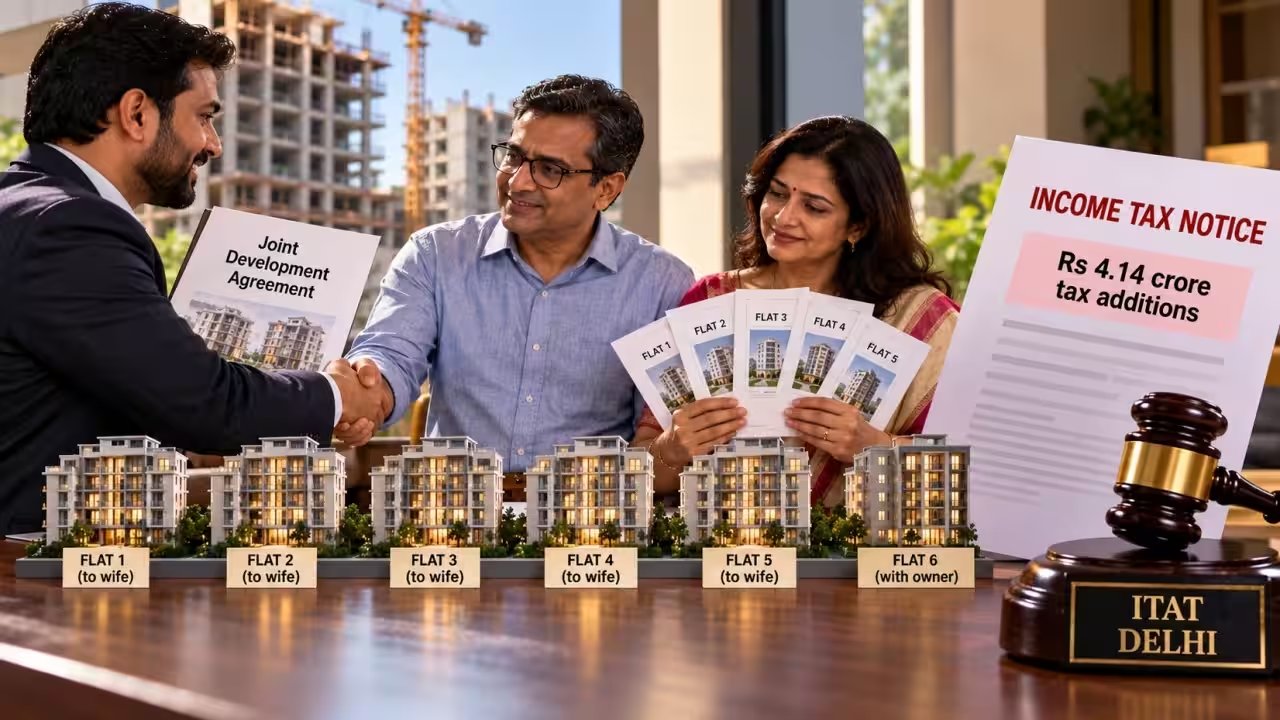
Mr. Kumar had entered a 2016 joint development agreement, contributing his agricultural land while the developer built a multi‑storeyed complex. In return he received six flats; five of them were transferred to his wife in 2020. The assessing officer treated the arrangement as a conversion of land into stock‑in‑trade, adding Rs 1.93 cr as long‑term capital gains, and later treated the transfer to his wife as a sale, adding Rs 2.20 cr as business income, for a total of Rs 4.14 cr.
The Delhi Bench first examined whether a joint development agreement can automatically convert a capital asset into stock‑in‑trade. It cited the Global Health Pvt. Ltd. decision, stressing that a taxpayer not engaged in real‑estate business cannot be deemed to have converted land into inventory simply by entering such an agreement. The tribunal found no evidence of business infrastructure, no trading account, and no stock register, concluding that the land remained a capital asset.
For the second addition, the tribunal turned to earlier ITAT rulings on intra‑family transfers. Mr. Kumar produced his wife’s affidavit and bank statements proving no consideration was paid when five flats were transferred. The tribunal held that the mere execution of a sale deed does not make a genuine sale if no payment is made, and therefore the transfer should not be taxed as business income.
The ruling eliminates the Rs 4.14 cr charge and clears the taxpayer from further scrutiny for AY 2021‑22. It also signals to other landowners that a joint development agreement alone does not trigger stock‑in‑trade status, and that intra‑family transfers without consideration may not constitute taxable sales. The assessment case is now closed; the taxpayer can file no further appeals.
The decision has already prompted comments from the tax department, which will need to revisit its methodology for similar joint‑development deals. Meanwhile, Mr. Kumar said the transfer to his wife was a precaution to secure the flats for a future mortgage, a move that the tribunal has now vindicated.