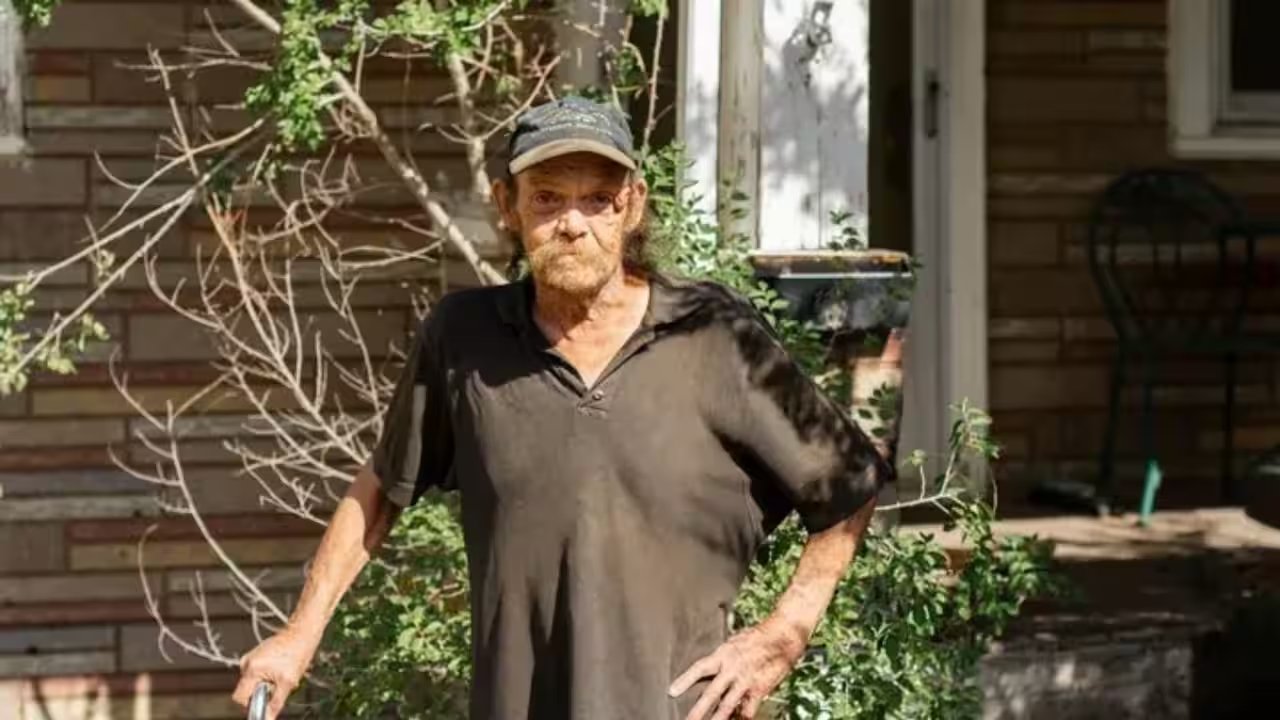
Kevin Fair and his wife Terry lost their mortgage-free Scotts Bluff County home in 2018, a property valued at $59,759, to settle a $588.21 property tax bill. The debt ballooned to $5,268 through interest and fees before Continental Resources, a private buyer, seized the deed. The Nebraska Supreme Court issued a ruling on August 23, 2024, in Continental Resources v. Fair, 317 Neb. 391, reviving the couple’s claim that the state deprived them of property without just compensation.
The legal battle began in March 2015 when the county treasurer sold the tax certificate to Continental Resources. Nebraska law allowed this sale, and Continental paid subsequent taxes, stopping the county from billing the Fairs directly. Three years later, Continental sent a notice giving the couple three months to redeem the property by paying the full $5,268. They failed to pay within the deadline, and the county issued the tax deed to the company in July 2018.
The case traveled to the US Supreme Court after the Nebraska high court initially upheld the lower court’s dismissal in 2022. The US Supreme Court granted review and vacated that ruling, citing its 2023 decision in Tyler v. Hennepin County. That precedent established that homeowners can challenge takings when the government retains property value exceeding the tax debt owed.
The Nebraska Supreme Court now found that Fair had a protected property interest in the home’s value above the tax debt. The justices determined that Continental’s actions were sufficiently connected to the state tax system to constitute state action. This allowed the takings claim to proceed to trial, though the court dismissed Fair’s other constitutional arguments, including those under the Excessive Fines Clause.
The ruling does not award a specific dollar amount but creates a path for the Fairs to seek compensation for the gap between the $59,759 home value and the $5,268 debt. The case remains docketed as S-21-074, with further proceedings pending to resolve the factual issues surrounding the compensation claim. The decision highlights the ongoing tension between private tax lien sales and constitutional protections for property owners in Nebraska.