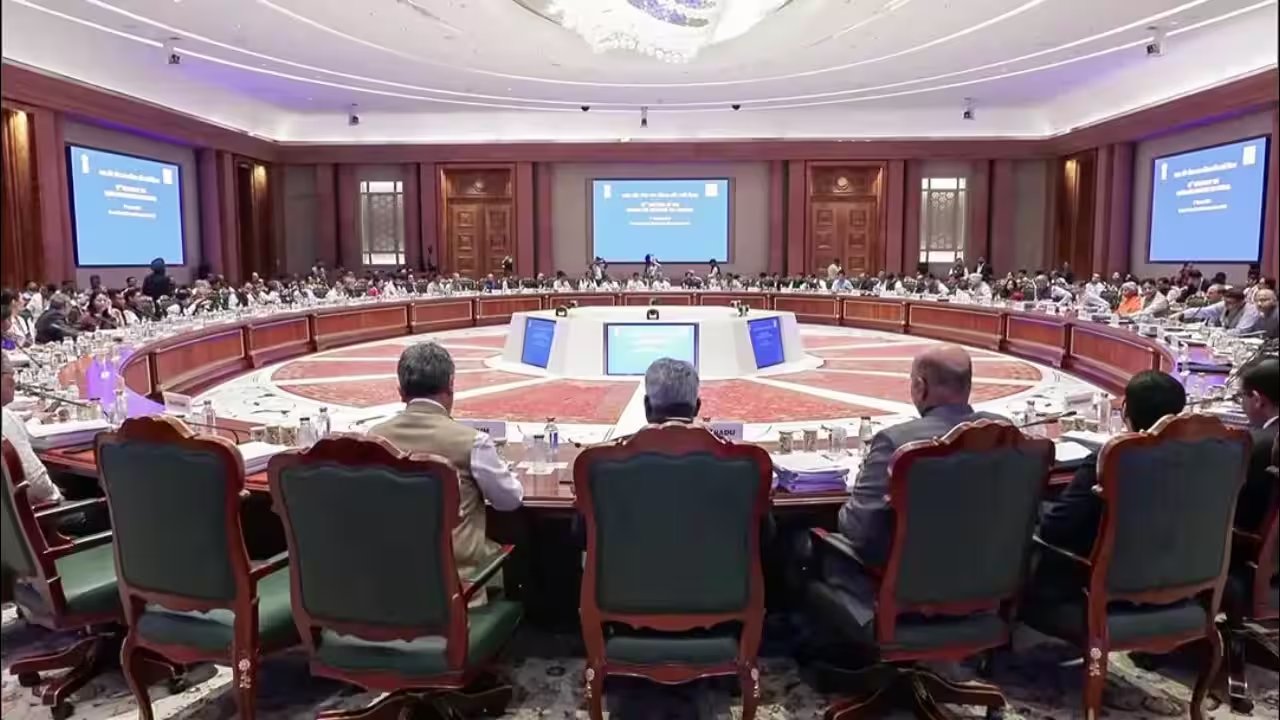
The GST Council voted on Friday to strip tax officers of their power to arrest taxpayers under Section 69 of the Central GST Act. This decisive move, announced by Finance Minister Nirmala Sitharaman after a six-hour session, marks a sharp departure from the punitive tone of the early GST years. The Council also hiked the monetary threshold for prosecution five-fold to ₹5 crore, effectively decriminalizing minor compliance errors.
But the relief extends beyond avoiding handcuffs. Sitharaman confirmed that 90% of refund claims will now be processed within three days, cutting the acknowledgement period from 15 days to 10. To further reduce friction on Indian highways, the Council barred officials in transit states from intercepting trucks unless a joint commissioner issues a warrant based on specific information. This directly addresses the long-standing complaint of arbitrary stoppages that plagued logistics chains.
Prime Minister Narendra Modi hailed the decision on social media, framing it as a shift toward "trust-based administration." He emphasized that faster decisions and automated refunds would lower compliance costs for businesses. While the Council reached unanimity on most points, it deferred a proposal to restrict input tax credit (ITC) only to entities that fail to deposit collected taxes. That specific issue went to an officer’s panel, with recommendations due in three months to align with the April rollout.
For the services sector and e-commerce sellers, the changes are equally significant. Businesses with turnover under ₹5 crore will be allowed to file annual returns, and e-commerce vendors will no longer need multiple state registrations. The Council also capped the maximum general penalty at ₹10,000, down from ₹25,000, and introduced a 5% reduced penalty for voluntary tax payment within 30 days in non-fraud cases. These reforms aim to make GST more transparent and citizen-friendly, as promised by the government.
The new framework takes effect in April, giving states and the Centre time to overhaul their systems. While the immediate removal of arrest powers is the headline, the true test will be the operational efficiency of the new refund and credit mechanisms. Businesses can expect a less adversarial relationship with tax authorities, but they must adapt to the new digital workflows and reduced penalty structures starting next fiscal year.