Finance Minister Bruno Le Maire said on Tuesday that France’s public debt will exceed 122 % of GDP by the end of the year, a new record. The announcement came as the IMF lowered its growth forecast to 0.4 % for 2024, the weakest among advanced economies.
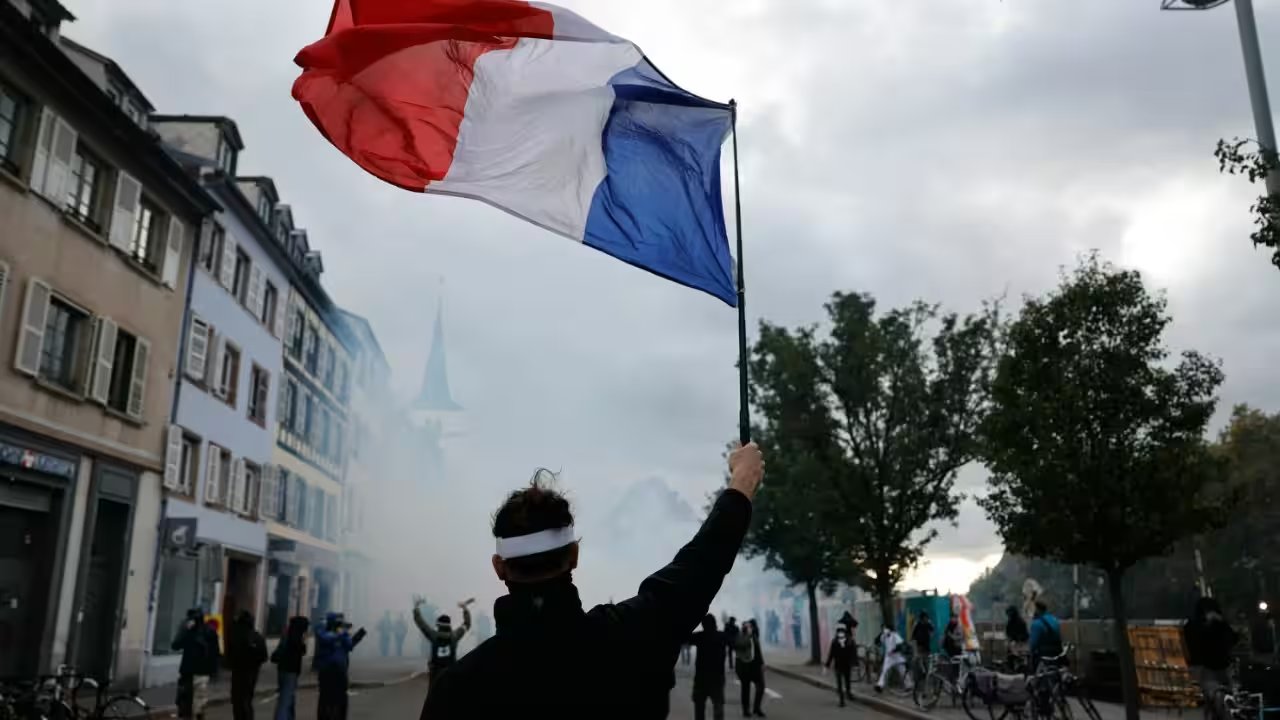
The warning arrived amid a wave of student demonstrations that began with school blockades in March and escalated into violent clashes by Saturday. The protests, driven by rising living costs, have sparked a nationwide debate over the cost of public services and the country’s fiscal trajectory.
The debt, now at 3.6 trillion euros, sits at 119 % of GDP according to June figures, but officials warned it could climb to 122 %. Carsten Brzeski, global macro chief at ING, cautioned that France’s fiscal path mirrors Greece’s crisis, though he denied the comparison.
Government spending accounts for 57.2 % of GDP, far above the EU average of just under 50 %. Meanwhile, tax revenue and social contributions reach 45.2 % of GDP, leaving limited room for further tax hikes.
The 10‑year government bond yield hit 4.96 %, a steep rise that raises borrowing costs. In contrast, Germany’s Bund yields 3.4 %, underscoring the widening cost gap between the two largest EU economies.
Le Maire will table a revised fiscal strategy to Parliament on July 12, with a vote expected in September as the next presidential election looms. A 17‑year‑old student from Lyon said the protests reflect a generational frustration with rising rents and stagnant wages.