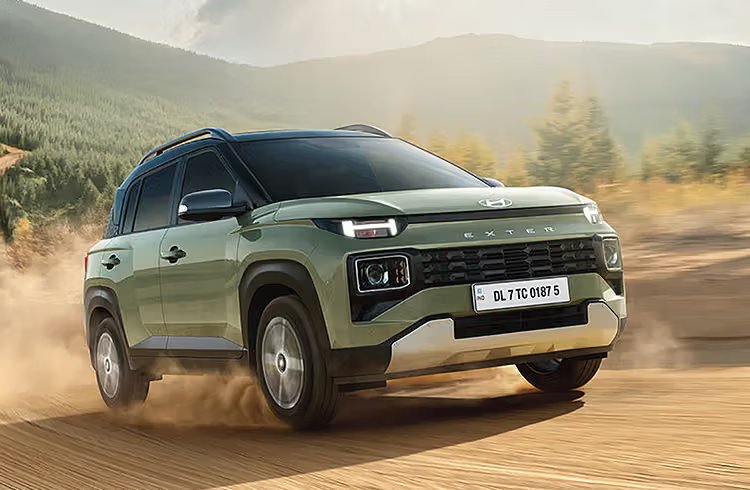
Hyundai Motor India’s Q2 FY27 net profit fell 24% to ₹1,196.16 crore as the cost of raw materials jumped 29% to ₹15,730.91 crore, while operating revenue still grew 18% to ₹20,696 crore.
The sharp rise in expenses outpaced the 18% revenue lift, squeezing the company’s profit margin. Total consolidated expenses climbed 24% to ₹19,302 crore, matching the steep cost climb.
For buyers, the numbers mean Hyundai may have to rethink discount strategies on key models like the Creta, i20, and the upcoming iX5. Competitors such as Tata and Maruti are also feeling the pinch, but their price elasticity gives them a slight cushion.
On the policy front, the latest EV duty structure and the global supply‑chain bottleneck for battery cells are adding to the cost of manufacture. That could translate into a modest price hike for future electric models, or a shift toward more cost‑efficient variants.
Looking ahead, Hyundai is likely to focus on cost‑control measures and could delay the launch of new models until material prices stabilise. The next wave of vehicles is expected to roll out in 2027, with city‑wide availability starting in major metros by Q3 2027.